Why You Should Replace Your Medicare Advantage Plan with a Medicare Supplement

The Annual Enrollment Period (AEP), which is from October 15th through December 7th each year, is almost here!

If you currently have a Medicare Advantage (MA) plan, you should switch back to Original Medicare and get a Medicare Supplement plan instead!

IMPORTANT: If you have a Medicare Supplement plan (aka “Medigap” because it picks up the “gap” in Medicare coverage) the AEP does not apply to you unless you want to enroll in or change your Prescription Drug Plan (PDP).

Why Medicare Supplement Plans Are Better

With Original Medicare (Part A and Part B) and a Medicare Supplement, you have much more freedom of choice and lower costs than you do with an MA plan!

NOTE: Medicare Part A is hospital insurance and Part B is medical insurance.

Which Plan Gives You the Most Freedom?

With an MA plan, you are locked into the plan’s network of doctors, specialists, hospitals, and care facilities. If you want to see a specialist, you often have to see your preferred care provider first, who acts as a gatekeeper, before you can see a specialist within your network. If you want to see a specialist or doctor that is outside of your network, good luck! That will cost you a lot more in out-of-pocket (OOP) costs.
gatekeeper_

With a Medicare Supplement plan, you can go to ANY doctor, specialist, hospital, or care facility in the US as long as they accept Medicare!

For example, the MD Anderson Cancer Treatment Center in Texas accepts Medicare and therefore, they accept ALL Medicare Supplement plans. They don’t, however, accept most MA plans!

Which Plan Has Lower Out-Of-Pocket Costs?

With an MA plan, your OOP costs can be as high as $6,700 per calendar year and even higher if you go to doctors and/or care facilities that are outside of your network! With a Plan F or Plan G Medicare Supplement (the two best Medigap plans), the most you would normally pay in OOP costs in a calendar year is either $0 with Plan F or $183 with
Plan G!
out of pocket costs

NOTE: The $183 is the Medicare Part B (Medical) deductible, which is $183 per calendar year in 2017. That amount can change from year to year, but historically, it has always been very stable.

Maximum Out-Of-Pocket Costs for MA Plans in San Diego

The following data was obtained from the Medicare.gov website and shows the current OOP costs for MA plans in the 92009 zip code in San Diego. These costs currently range from $3,300 to $6,700 per calendar year!

If you go out-of-network with your MA plan, your OOP costs will be even higher!

Current (in-network) Maximum OOP Costs for MA Plans in the 92009 Zip Code:

  • AARP MedicareComplete SecureHorizons Essential (HMO) – $4,900
  • AARP MedicareComplete SecureHorizons Plan 4 (HMO) – $3,400
  • AARP MedicareComplete SecureHorizons Premier (HMO) – $4,300
  • AARP MedicareComplete SecureHorizons Value (HMO) – $5,300
  • Aetna Medicare Choice Plan (PPO) – $6,000
  • Aetna Medicare Select Plan (HMO) – $3,400
  • Anthem MediBlue Coordination Plus (HMO) – $6,700
  • Anthem MediBlue Plus (HMO) – $3,400
  • Blue Shield 65 Plus (HMO) – $3,400
  • Brand New Day Classic Care Drug Savings (HMO) – $3,400
  • Brand New Day Classic Choice for Medi-Medi (HMO) – $6,700
  • Care1st AdvantageOptimum Plan (HMO) – $3,400
  • Coordinated Choice Plan (HMO) – $6,700
  • Health Net Healthy Heart (HMO) – $3,400
  • Health Net Seniority Plus Sapphire (HMO) – $6,700
  • Health Net Seniority Plus Sapphire Premier (HMO) – $6,700
  • Humana Gold Plus H5619-016 (HMO) – $4,900
  • Humana Value Plus H5619-037 (HMO) – $6,700
  • Kaiser Permanente Senior Advantage San Diego (HMO) – $4,900
  • Scripps Classic offered by SCAN Health Plan (HMO) – $3,400
  • Scripps Plus offered by SCAN Health Plan (HMO) – $6,700
  • Scripps Signature offered by SCAN Health Plan (HMO) – $4,000
  • Sharp Direct Advantage Gold Card (HMO) – $3,400
  • Sharp Direct Advantage Platinum Card (HMO) – $3,300
  • Sharp SecureHorizons Plan by UnitedHealthcare (HMO) – $3,400

In contrast, in a calendar year, your maximum OOP costs are either $0 with a Plan F Medicare Supplement or $183 with a Plan G Medicare Supplement!

Is Your MA Plan’s Maximum OOP Costs Really No More Than $6,700 Per Year?

If you stay within your MA plan’s network, your maximum OOP costs are not supposed to be more than $6,700 per calendar year. However, if you go outside of the plan’s network, your OOP costs can be significantly higher than that!

Suppose that you get really sick and need expensive treatment such as Chemotherapy, etc. in the second half of the year. You could end up paying up to $6,700 (or whatever your plan’s maximum OOP cost is) by the end of the calendar year and guess what? Your OOP maximum zeros out in January, and it starts all over again!

If you are still receiving expensive medical care in the beginning of the year, you could potentially end up paying your maximum OOP cost two different times in a
12-month period! For example, if your maximum OOP cost is $6,700, your total OOP cost in a 12-month period, not a calendar year, could be more than $13,400!

Which Plan Has Lower Co-Payments?

If you have an MA plan, you will make a co-payment almost every time you go to the doctor, see a specialist, a physical therapist, etc. With most Medicare Supplement plans, there are no co-payments for doctor’s visits, etc.
Co Payment

How Difficult is it to Switch From an MA Plan to Original Medicare and a Medicare Supplement Plan?

That depends if you are in a Special Enrollment Period (SEP).

Special Enrollment Period

If you currently have an MA plan, and you are in a SEP, you can switch to Original Medicare and to any six of the 10 “standardized” Medicare Supplement plans any time of the year, REGARDLESS of your health.

The six “guaranteed issue” Medicare Supplement plans are plans A, B, C, F, K, and L. In other words, if you are in a SEP, you are guaranteed the right to get a Plan F Medicare Supplement, but not a Plan G supplement, etc.

NOTE: You could apply for Plan G, but you would be medically underwritten, and you could be turned down for certain medical conditions.

The 10 Standardized Medicare Supplement Plans

Nationwide, there are 10 “standardized” Medicare Supplement plans to choose from (Plans A through N). The term “standardized” means that the benefits and coverage for every Plan F, Plan G, etc. is exactly the same with every insurance carrier. Unlike MA plans, which are not standardized, it’s much easier to compare “apples with apples” with Medicare Supplement plans.

Medicare Supplement rates are not standardized. They vary significantly between insurance carriers. For that reason, it’s very important to shop around every year!
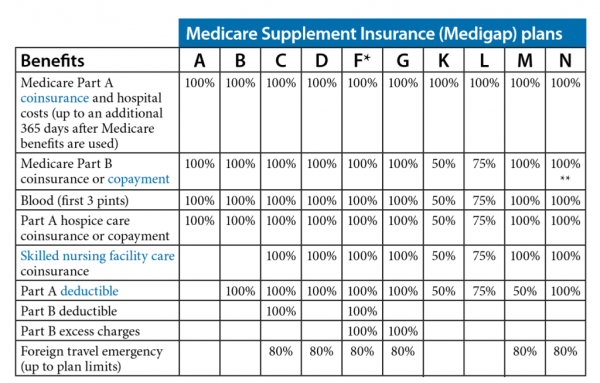
2017-Medicare-Supplement-Chart

NOTE: In the preceding chart, notice that the only difference between Plan F and Plan G is the $183 per calendar year Part B deductible.

SEP Situations

Here are some SEP situations that would guarantee you the right to switch back to Original Medicare and a Medicare Supplement plan:

  • The plan is leaving the Medicare program or stops service in your area.
  • You move out of the plan’s service area.
  • You leave the plan because the company has not followed certain rules or has misled you.
  • You decide to switch to Original Medicare within the first year of joining an MA plan when first eligible for Medicare Part A at age 65.

If you are in one of these situations, you cannot be turned down for Medicare Supplement insurance coverage, regardless of your health!

If You Are Not In a Special Enrollment Period

If you are not in a SEP, you will have to wait until the AEP (between October 15th and December 7th) to switch back to Original Medicare (Part A and Part B) on January 1st of the following year.

Although you can switch back to Original Medicare, there is no guarantee that you will be able to get a Medicare Supplement plan because you will be medically underwritten, and you must be in relatively good health to qualify for a Medicare Supplement plan.

If You Have Serious Health Conditions, You May Not Be Able to Get a Medicare Supplement Plan!

If you are not in a SEP and you are coming off of an MA plan during the AEP, you would normally have to meet minimum underwriting requirements to qualify for a Medicare Supplement plan, and you could be turned down for coverage.

If you live in California and you have serious health issues, more than likely, I can still get you a Medicare Supplement without having to answer any medical questions on the application! Call me for more details!

The Pros and Cons of MA Plans and Medicare Supplement Plans

Is there really an advantage to having a Medicare Advantage plan? Let’s take a look at the pros and cons of each, and you can decide for yourself.
Pros-and-Cons-of-Alternative-Lending

MA Plan Advantages

Here are some benefits of having an MA plan:

  1. MA premiums can be very low, and some plans have no monthly premiums at all.
  2. Some MA plans include Medicare prescription drug coverage (Part D).
  3. Maximum OOP costs are “limited.” Plans vary, but in 2017, the most you can pay in OOP costs is $6,700 per calendar year. (I wouldn’t really call this a “benefit” since $6,700 is a lot of money! With a Plan F Medicare Supplement, you won’t pay any OOP costs!)
  4. Some MA plans offer additional benefits such as vision, hearing, dental, and other health and wellness programs. (Note that some Medicare Supplement plans also offer additional benefits such as free gym memberships, vision, and hearing aid benefits.)

Medicare Supplement Plan Advantages

Here are some benefits of having a Medicare Supplement plan:

  1. You have much more FREEDOM of choice with a Medicare Supplement than you do with an MA plan because you can go to ANY doctor, hospital, specialist, or care facility in the United States as long as they accept Medicare. (You can’t do that with an MA plan.)
  2. You have much for financial stability with a Medicare Supplement than an MA plan because there are no unexpected spikes in costs and OOP expenses for co-payments, hospitalizations, surgeries, chemotherapy, etc.
  3. With a Plan F or Plan G Medicare Supplement, other than your premiums, your maximum OOP costs in a calendar year will be either $0 (Plan F) or $183 (Plan G) per calendar year in 2017. With an MA plan, your maximum OOP costs can be as high as $6,700 per calendar year!
  4. Chemotherapy is very expensive. With an MA plan, you have to pay the entire 20% Medicare Part B co-payment for chemotherapy, which can cost thousands of dollars. With a Plan F or Plan G Medicare Supplement, the most you will pay for Chemotherapy is either $0 (Plan F) or $183 (Plan G)!
  5. You are not limited to a specific geographic region or a restrictive network of doctors, hospitals, specialists, care facilities, etc. like you are with an MA plan. With most MA plans, you must use their providers or you may pay more or all of the costs if you go out of their network.
  6. With a Medicare Supplement, you can go directly to the specialist of your choice, ANYWHERE in the United States, as long as they accept Medicare. With most MA plans, you must go through your primary care doctor first (the “gatekeeper”) before you can see a specialist within your network.
  7. There are no HMO or PPO plans or networks with Medicare Supplements. If you have an MA plan and you go to a doctor, other health care provider, facility, or supplier that doesn’t belong to the plan’s network for non‑emergency or non-urgent care services, your services may not be covered, or your costs could be higher.
  8. If you want to go to a renowned treatment center such as the MD Anderson Cancer Treatment Center in Texas, you can do so with any Medicare Supplement, as long as they accept Medicare. You can’t do that with most MA plans.
  9. If you move to another part of the country, you can keep your Medicare Supplement, but you cannot keep your MA plan if you move out of your network.
  10. There are only 10 “standardized” Medicare Supplement plans to choose from, (Plan A through Plan N). Since Medicare Supplements are standardized, the coverage and benefits for every Plan F, Plan G, etc. is exactly the same with every insurance carrier, so it’s much easier to shop around and compare “apples with apples.” MA plans are not standardized, and the co-payments, deductibles, out of pocket costs, etc. vary significantly between MA plans, and they change every year making them unnecessarily complicated and confusing.
  11. Your Medicare Supplement plan cannot be cancelled as long as you pay your premiums. MA plans are annual contracts, and they can be cancelled or benefits changed at the end of each calendar year.
  12. There are no provider networks with Medicare Supplements. With MA plans, providers can join or leave a plan’s provider network anytime during the year meaning that you could have to start shopping around for a new doctor while simultaneously undergoing Chemotherapy or other specialized medical treatments.
  13. There is no AEP for Medicare Supplements, and you don’t have to shop around every year and make sure that your coverage, co-payments, co-insurance, deductibles, and benefits haven’t changed since the previous year. If there are any Medicare changes from one calendar year to the next, your Medicare Supplement will automatically pay the difference.
  14. You can travel around the US for as long as you want (or even move to a different geographic location), and your Medicare Supplement cannot be cancelled for leaving your “service area.” With most MA plans, if you travel outside of the MA plan’s service area for more than six months, you could be disenrolled from the plan.
  15. With most Medicare Supplements, there are no co-payments when you go to the doctor. With most MA plans, you have to pay co-payments when you go to the doctor.
  16. With Medicare Supplements, pre-certification is not required for surgeries, etc. as long as the procedure is “medically necessary.” With most MA plans, pre-certification is required for surgeries or before getting expensive treatments.
  17. You can switch Medicare Supplement plans or insurance carriers any time of the year as long as you meet minimum health and underwriting requirements. With an MA plan, you can only join or leave an MA plan during the AEP. Otherwise, you are locked into your plan for the entire calendar year, except for certain circumstances, such as moving out of your plan’s service area, etc.)

As you can see, you are much better off with a Medicare Supplement plan than you are with a Medicare Advantage plan!

Conclusion

If you currently have a Medicare Advantage (MA) plan, you have given up your Original Medicare rights that you have worked so hard for, and you are compromising your freedom to go to the best doctors, hospitals, specialists, neurosurgeons, care facilities, etc. in the United States.

I would strongly urge you to switch back to Original Medicare and get a Medicare Supplement plan during the upcoming AEP, between October 15th and December 7th)! Contact me TODAY for more information or a free quote!

As an independent insurance agent specializing in Medicare Supplements, I work with ALL of the major insurance carriers, not one particular company. I will shop around for you, every year, and save you money on your Medicare Supplement insurance!

If you live in California and you have a serious medical condition, more than likely, I can still get you a Medicare Supplement at a competitive price without answering any of the health questions on the application!

I hope that you have found this article to be helpful and informative. Please feel free to forward this article to anyone who may be interested.

Your comments and feedback are appreciated! If you have any questions, please contact me… I’m always happy to help!

Thank you!

Ron Lewis
www.MedigapExpress.com
Ron@RonLewisInsurance.com
866.718.1600 (Toll-free)

–
Hello Medicare, and Goodbye Obamacare!

In several months from now, a good friend of mine will be turning 65 years old. While he is not anxious to get any older than he already is, he is happy about one thing… he will be getting off of Obamacare and onto Medicare!

65th-birthday-latex-balloons

My friend used to have a really good, low-deductible health insurance plan that was very affordable. But under Obamacare, all of that changed. The quality of his health insurance decreased significantly while his Affordable Care Act (ACA) premiums, co-payments, and deductibles increased dramatically. But fortunately, he now has maternity coverage, which is something that he never had before! Sorry about the sarcasm!

Pregnant man

When he goes onto Medicare, it will be just the opposite; the quality of his health insurance will increase significantly while the cost of his premiums, co-payments, co-insurance, and deductibles will all decrease!

Current Coverage

For example, he currently has a Bronze 60 ACA plan. The annual deductible is $4,800 per calendar year if he goes to “participating” providers and $9,000 per calendar year if he goes to “non-participating” providers! According to his health plan, “You must pay all the costs up to the deductible amount before this plan begins to pay for covered services you use. The integrated deductible applies to both medical and pharmacy services.” Therefore, the deductibles apply to prescription drug coverage as well.

Once the deductible is met, my friend must pay 40% of the remaining costs until he has reached the maximum out-of-pocket (OOP) cost, which is $6,550 per calendar year for “participating” providers and $9,650 per calendar year for “non-participating” providers.

NOTE: According to his current health insurance plan, OOP costs do not include “Premiums, balance-billed charges, some co-payments, charges in excess of specified benefit maximums, and health care this plan doesn’t cover.” So, total OOP costs are really much higher than $6,550 or $9,650 per calendar year when you factor in premiums and other miscellaneous costs.

The deductible and OOP costs start all over again every January. If he got really sick in the last six months of the year, there is a real possibility that he could reach his maximum OOP costs of $6,550 (or $9,650) again in the first six months of the following year. That means that he could potentially have total OOP costs in excess of $13,100 to $19,300 in a twelve-month period, not including his premiums!

My friend has a subsidized plan through Covered California. Although he pays $268.52 per month for his Bronze 60 PPO plan, the full premium that others are paying for the same identical (non-subsidized) plan is $784.79 per month, which isn’t exactly cheap for a high-deductible, catastrophic plan! I’m pretty sure you can buy or lease a luxury automobile for a lot less than that!

Mercedes

Medicare Coverage

In contrast, he won’t have to pay anything for his Medicare Part A (Hospital) insurance, and he will pay $134.00 per month for his Medicare Part B (Medical) insurance. In addition to his Original Medicare, he will need to take out a Medicare Supplement plan to pick up the difference in co-payments, deductibles, and co-insurance that Medicare does not pay.

Medicare Supplement Coverage

Of the 10 standardized Medicare Supplement plans (aka Medigap plans because they pick up the “gaps” in coverage that are not covered by Medicare), Plan F and Plan G are the two best plans:

  • Plan F pays for ALL of the co-payments, deductibles, and co-insurance that is not covered by Medicare. With Plan F, there are NO DEDUCTIBLES OR OUT-OF-POCKET COSTS!
  • Plan G is identical to Plan F except for the $183 per calendar year deductible for outpatient treatment such as physician services, inpatient and outpatient medical and surgical services and supplies, physical and speech therapy, diagnostic tests, and durable medical equipment.

NOTE: In 2017, the Part B deductible is $183 per calendar year. This amount can change from year to year, but historically, it has been very stable. With Plan G, once you have met the $183 per calendar year deductible, there are no other out of pocket costs, and Plan G is exactly the same as Plan F. The monthly premiums for Plan G are usually significantly less than the monthly premiums for Plan F, so Plan G usually ends up being more cost effective than Plan F.

For this reason, many people with Plan F have been switching to Plan G. Also, beginning on January 1st, 2020, Plan F will no longer be available for new people who are turning 65.

Although my friend’s ACA health plan is a PPO, he is still restricted to doctors, specialists, hospitals, care facilities, etc. that are within his health plan’s network. If he goes out of the network or goes to “non-participating” providers, he pays even more!

With Original Medicare and Medicare Supplements, there are no networks, HMO’s, or PPO’s, so my friend will have much more freedom of choice than he presently has with his ACA plan.

freedom

With a Medicare Supplement plan, you can go to ANY doctor, specialist, care facility, or hospital in the United States, as long as they accept Medicare! If you later move to another state, you can keep your Medicare Supplement plan and use it ANYWHERE in the US!

Medicare Supplement Premiums

In California, Medicare Supplement rates are based primarily on your age and zip code. If my friend decides to splurge and go with Plan F (the “Cadillac” plan) he will have a $0 deductible and no out-of-pocket costs! For age 65, his monthly premium will be as low as $132.00 per month!

Rates can vary significantly between insurance carriers for the same identical plan and coverage, so it’s important to shop around every year!

If my friend wants to save money on his Medicare Supplement premiums by signing up with Plan G, his maximum calendar year deductible AND out-of-pocket costs combined will be $183 per calendar year, and his monthly premium will be as low as $119.36 per month!

Plan F or Plan G

Scenario #1 – Total Costs if My Friend Signs up with Plan F

If he decides to sign up with Plan F, the most expensive Medicare Supplement plan, his total monthly premiums for his Medicare Part A ($0), Medicare Part B ($134.00), and his Plan F Medicare Supplement ($132.00) will be $266.00 per month!

NOTE: If he wants to, my friend can also pick up a good Prescription Drug Plan (PDP) for $17.00 per month.

Scenario #2 – Total Costs if My Friend Signs up with Plan G

If he decides to sign up with Plan G, the most popular Medicare Supplement plan, his total monthly premiums for his Medicare Part A ($0), Medicare Part B ($134.00) and his Plan G Medicare Supplement ($119.36) will be $253.36 per month!

Conclusion

My friend is currently paying $268.52 per month for a high-deductible, catastrophic ACA health insurance plan that is basically worthless.

If he decides to sign up for a Plan F Medicare Supplement with no deductibles or out-of-pocket costs, his total cost for coverage under Medicare and his Medicare Supplement will be $266.00 per month!

If he decides to sign up for a Plan G Medicare Supplement with a $183 per calendar year deductible and no out-of-pocket costs, his total cost for coverage under Medicare and his Medicare Supplement will be $253.36 per month!

And now you know why my friend is smiling about his upcoming 65th birthday…
“Hello Medicare, and good riddance Obamacare!”

*****************************************************

Let me do the shopping for you and save you money on your Medicare Supplement! Contact me today for a for a free insurance quote and price comparison!

Ron Lewis
www.MedigapExpress.com
Ron@RonLewisInsurance.com
866.718.1600 (Toll-free)

Medicare Supplements – Why Pay Wholesale When You Can Pay Retail?

Yes, you read the title correctly. When it comes to Medicare Supplement plans, which are also known as Medigap plans because they pay for the “gaps” in coverage that are not paid for by Medicare, some of my clients prefer to pay retail instead of wholesale! That’s right, “Why pay less when you can pay more?”

retail

Most people that I meet are very happy to save a lot of money on their insurance premiums, but there are always some that really don’t seem to care. Or maybe they are skeptical because it just “seems too good to be true,” which I can totally understand.

A Tale of Two Cities, I Mean Two Clients…

I was working with two different clients yesterday, Client “A” and Client “B.”

two clients

Client “A”

Client “A” has Plan F with Blue Shield of CA, and his monthly premium is $279 per month. I shopped around for him and found several other insurance carriers that are offering Plan F at much lower rates. The lowest rate that I found for him is $179.33 per month. That is a savings of $99.67 per month or $1,196.04 per year for the same identical plan and coverage!

Many people who have Plan F have been switching to Plan G because both plans are identical except there is no deductible with Plan F, and there is a small $166 (Part B) deductible with Plan G. That is the only difference between the two plans!

However, Plan G is usually much more cost effective (cheaper) because the rates are lower. So even if you pay the $166 deductible, in most cases, you still end up spending much less money with Plan G than Plan F.

In addition to getting the current Plan F rates for Client “A,” I also provided him with the current Plan G rates for comparison. If he switched from Plan F to Plan G, he would have saved even more money! The best Plan G rate is $156.70 per month. That would be a gross savings of $122.30 per month or $1,467.60 per year! If he spent the $166 deductible, his net savings would still be $1,301.60 per year! In this particular case, Client “A” would have saved even more money by switching from Plan F to Plan G.

Inexplicably, Client “A” decided to keep his current plan for another year!

Client “B”

Client “B” also has Plan F with Blue Shield of CA, and her rate is $219 per month. I shopped around for her and, like Client “A,” I found several other insurance carriers that are also offering Plan F at much lower rates. The lowest rate that I found for Client “B” is $170.99 per month. That is a savings of $48.01 per month or $576.12 per year for the same identical Medicare Supplement plan and coverage!

Client “B” also had the option to switch from Plan F to Plan G, and again, she would have saved even more money on her premiums by doing so. Her current Plan F rate is $219 per month, and the best Plan G rate for her is $147.19 per month. That would be a gross savings of $71.23 per month or $854.76 per year! If she spent the entire $166 deductible, her net savings per year would still be $688.76 per year!

Just like Client “A,” Client “B” also decided to keep her current plan for another year!

Some Common Misconceptions

It’s very baffling to me when I can literally save someone hundreds and even thousands of dollars a year on their premiums for the same exact plan and coverage, and for whatever reason they are not interested in doing so.

If my auto and homeowner’s insurance agent told me he could save me $100 a month on my premiums, I would be thrilled to be able to save that much money. I guess that some people just aren’t as happy about saving money as I am!

Save-Money

Misconception #1 – By Switching Medigap Plans, I Won’t Be Able to Go to the Same Doctors

Some people are reluctant to change Medigap plans because they are afraid that they won’t be able to continue seeing the same doctors. This is a misconception because you can go to ANY doctor or hospital in the US with your Medicare Supplement as long as the doctor or hospital accepts Medicare. If your doctor accepts your current Medicare Supplement plan, then they have to accept ANY Medigap plan or insurance carrier that you have, PERIOD.

Misconception #2 – The Rates Are Too Good to Be True

If the new rates are significantly lower than the current plan, some people think it’s either too good to be true or a huge rate increase is soon to follow. This is also a misconception because most of the carriers that I work with lock in their rates for the first 12 months, so there wouldn’t be any unexpected rate increases.

Misconception #3 – My Coverage Will Not Be the Same

Another common misconception is that the coverage will not be the same, even if someone is switching from Plan F to Plan F or Plan G to Plan G, etc. There are 10 “standardized” plans to choose from, Plan A through Plan N. This means that the coverage for every standardized plan is exactly the same with every insurance carrier. So if someone has Plan F with Blue Shield and they want to switch to Plan F with Mutual of Omaha, etc., the coverage is exactly the same. Plan F is Plan F is Plan F…Period!

One of the other reasons people don’t want to switch their Medicare Supplement plan is because they fear change. “Everything has been going great so far. Even though the rates are cheaper and the coverage is the same, why take a chance by going with a different carrier?”

If you decide to switch carriers, the transition is seamless. Your coverage with the first insurance carrier will end at the end of the month, and the new coverage begins on the 1st of the following month. There are no forms or paperwork to fill out. When you go to the doctor after your new coverage begins, they will make a copy of your new Medicare Supplement card, and after that, everything will be the same as before.

The California Birthday Rule

In California, there is a law called the California Birthday Rule. If you have a Medicare Supplement, you are lucky to live in California for more reasons than just the beautiful weather and the great beaches!

happy-birthday

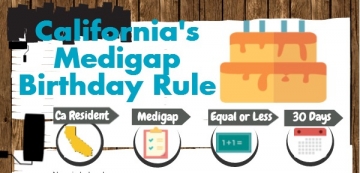
This law guarantees you the right to switch insurance carriers, EVERY YEAR, within 30 days of your birthday (before or after) REGARDLESS OF YOUR HEALTH and without answering any health questions on the application! This is known as your annual open enrollment period. If another insurance carrier is offering the same plan that you currently have, or if they are offering another plan that has fewer benefits, you are guaranteed the right to switch carriers every year if you want to, and you cannot be turned down due to health reasons.

For example, if you have Plan F and another carrier is offering Plan F for a lower rate, you are guaranteed the right to switch to the other carrier every year around your birthday, without answering any health questions on the application. Likewise, you are guaranteed the right to switch to a plan with fewer benefits as well. So if you have Plan F, which has the most comprehensive coverage, you could switch to Plan G if you want to because Plan G has fewer benefits than Plan F.

NOTE: Under the California Birthday Rule, if you have Plan F, you can switch to any other plan, but if you have any other plan, you cannot use the California Birthday Rule to switch to Plan F because it has more benefits than any other plan.

You can actually switch insurance carriers or plans any time of the year, but if you do so at any time other than during the 30 days before or after your birthday, you will have to answer the health questions on the application, you will be medically underwritten, and you could be turned down for coverage due to medical reasons. If you have any serious health conditions, you should apply during the 30 days before your birthday!

In most other states, there isn’t a birthday rule. That means that once you sign up, if you later develop any serious health issues, you would have to meet minimum health and underwriting requirements if you wanted to change your Medicare Supplement plan or your insurance carrier. If your insurance rates increased significantly, you could be stuck paying very high premiums for many years! In California, that would never happen because you can always change your insurance every year around your birthday, regardless of your health!

Rates Vary Significantly Between Insurance Carriers For the Same Identical Plans and Coverage

In California, rates are based on “attained age,” which means that your rates are based on your current age, and they usually go up in price every year as you get older. As mentioned before, there are 10 “standardized” Medicare Supplement plans to choose from, Plan A through Plan N. When I say “standardized,” that means that the coverage for Plan F, Plan G, etc. is exactly the same no matter which insurance carrier that you are with.

Although the coverage is exactly the same with every insurance carrier, the rates (prices) vary significantly between insurance carriers!

dollars

For example, in the 92056 zip code the Plan F rates for a 72 year old man range in price from $164.06 to $278.86 per month! That is a difference of $1,377.60 per year for the same exact plan and coverage! In other words, some 72 year old individuals in the 92056 zip code are paying $164.06 per month for their Plan F coverage while others are paying $278.86 per month for their Plan F coverage!

Examples of How I Recently Saved Clients Money By Switching From Plan F to Plan F

Here are some examples of how I took advantage of the California Birthday Rule and saved my clients a lot of money on their annual premiums by switching them from Plan F with one carrier to Plan F with a different carrier:

  • $142.08
  • $257.64
  • $334.08
  • $338.64
  • $349.68
  • $432.84
  • $498.24
  • $501.78
  • $501.78
  • $516.96
  • $536.76
  • $879.84
  • $1,003.56

Examples of How I Recently Saved Clients Money By Switching From Plan F to Plan G

Here are some other examples of how I took advantage of the California Birthday Rule and saved my clients a lot in their annual premiums by switching them from Plan F with one carrier to Plan G with a different carrier:

  • $203.12
  • $278.96
  • $349.16
  • $425.48
  • $462.68
  • $600.00

Although it’s not the norm, the most I have ever saved one of my clients, a married couple, was over $5,300 per year just by switching from Plan G with one insurance carrier to Plan G with a different insurance carrier! As you can see, it’s really important to shop around and compare rates!

Sometimes I Feel Like “I Get No Respect!”

Once in a while, however, I feel like Rodney Dangerfield because “I get no respect!” Most of my clients are 65 or over and many are retired and on fixed incomes. The majority are very receptive to saving money on their insurance premiums, but once in a while, I have to practically beg people to let me save them hundreds and even thousands of dollars a year on their premiums, and quite honestly, that drives me crazy!

Rodney_Dangerfield2

For whatever reasons, some people, like Client “A” and Client “B,” are apparently not so budget conscious. I was very excited and happy to tell them how much money I could save them, and their response was basically “Let me think about it!”

Think about it? Really? What is there to think about! It seems to me that it’s pretty much a no-brainer. I can hear them now. “Do I want to save $1,200 per year on my premiums for the same exact plan and coverage? Hmm, this is really a tough one. What am I going to do with an extra $100 a month? This might complicate my taxes! Eh, who needs this kind of stress and aggravation!”

stress

I don’t want any of my clients to feel stressed or aggravated! If you’re one of those individuals that prefer to pay wholesale instead of retail, instead of the other way around, please don’t hesitate to contact me if you have any questions or if I can help in any way. If you’d like me to, I’m happy to do the shopping for you, EVERY YEAR, to save you money on your Medicare Supplement insurance!

NOTE: Although this article focuses primarily on Medigap plans in California, I am licensed and work with Medicare Supplement insurance plans outside of California as well. If you need premium rates for other states, I am happy to provide you with that information as well.

If you or someone that you know would like a free quote, please let me know. If you know anyone that might enjoy reading this blog, please feel free to forward it on! And please feel free to send me any of your questions, comments, and feedback!

Thank you,

Ron Lewis

Save Money On Your Medicare Supplement by Comparing Rates Each Year

One of the most rewarding parts of my job is helping my clients save money on their Medicare Supplement (Medigap) insurance premiums. Most of the time, I can usually save individual clients at least $30 to $50 per month ($360 to $600 per year) on their premiums. Occasionally, I have saved them as much as $1,000 to $1,200 per year on their premiums!

medigap

I don’t mean to come across as bragging, because I’m not. However, I am very happy and excited because this past week I was able to save one of my clients (a husband and wife on a fixed income) over $5,300 per year on their Medicare Supplement premiums!  I was able to do this just by simply switching them to the same exact plan that they had, but with a different carrier!

They had Plan G with another company for quite a few years, and they were very happy with the company and their coverage. Their insurance rates were very low when they originally took out their plans, and the company always paid their claims promptly and without a problem, just as most Medicare Supplement insurance companies do. However, over time, their rates crept up, slowly but steadily. Until this past week when they called me, they didn’t realize that they were literally paying thousands of dollars more for their insurance than they should be!

Most people shop around every year or two and compare rates on their auto and homeowner’s insurance. Medicare Supplements are no different. If you have a Medicare Supplement plan, it is critically important that you shop around every year and compare rates between various companies because insurance rates vary significantly from one carrier to the next for the same identical plan and coverage. For example…

For a 72 year old female living in the 92056 zip code, the current Plan F rates range from $164.06 per month to $245.50 per month! That is a difference of $81.44 per month or $977.28 per year more for the same exact insurance coverage!

Attained Age

In California, Medicare Supplement insurance premiums are based on attained age. This means that as you get older, your rates usually continue to go up every year. Many companies start off at the “younger” ages (65 to 70) with very competitive rates, but over time, the rates continue to go up. Every company is different, and some companies raise their rates a lot more than others.

If you become complacent and don’t shop around every year to compare rates, you are probably paying hundreds or even thousands of dollars more per year on your insurance premiums than you should be!

California Birthday Rule

In California, there is a law called the California Birthday Rule. This law allows anyone with a Medicare Supplement to switch to another insurance carrier every year within 30 days of their birthday (before or after), REGARDLESS OF THEIR HEALTH and without medical underwriting, if another insurance carrier is offering the same plan, such as Plan F, at a lower rate. During the annual 30-day open enrollment period, you are also guaranteed the right to switch to a “lesser” plan, such as from Plan F to Plan G, etc.

CA Birthday Rule

If you have a Medicare Supplement plan, you are guaranteed the right to shop around every year within 30 days of your birthday to save money on your insurance premiums. During this period, you cannot be turned down for coverage, regardless of your health.

You Can Apply for Medicare Supplement Plans All Year Long

Unlike Medicare Advantage plans that have an Annual Enrollment Period (AEP) from October 15th to December 7th every year for a January 1st effective date, you can apply for Medicare Supplement plans all year long. The only difference is that if you apply using the California Birthday Rule within 30 days of your birthday, you do not have to answer any of the health questions on the application, and you cannot be turned down for coverage due to health conditions.

If you apply for a Medicare Supplement plan any time of the year other than during your annual 30-day open enrollment period, you will have to answer the health questions on the application, and if you have certain health conditions, you could be turned down for coverage. If you are in relatively good health, you should not have any problem qualifying for a Medicare Supplement plan.

Guaranteed Issue Situations In California

In California, there are certain circumstances when you would qualify for a Medicare Supplement due to a guaranteed issue situation.

CA Bear

If you can answer YES to any of the following questions, you may be eligible for guaranteed issue:

  1. Has your employer-sponsored retiree plan that is supplementing Medicare involuntarily terminated?
  2. Has your employer-sponsored retiree plan stopped providing Medicare supplement benefits or the Medicare Part B 20% coinsurance for services?
  3. Have you lost eligibility for an employer-sponsored retiree plan due to divorce or death of a spouse or family member?
  4. Has your Medicare Advantage plan increased your premium or co-payments by 15% or more, reduced your benefits, or terminated its relationship with your medical provider who was treating you?
  5. Have you moved out of the area of your MA plan or Program for All-Inclusive Care for the Elderly (PACE) organization?
  6. Has your MA plan, Medicare SELECT Plan, PACE provider or any other health plan under contract with Medicare: (a) committed fraud; (b) ended or lost its contract with Medicare; (c) misrepresented the plan you bought, or (d) failed to meet its contractual obligations to Medicare beneficiaries, as determined by the federal government?
  7. Did you join a MA plan or PACE organization when you first became eligible for Medicare at age 65, and you want to switch to a Medicare Supplement policy during your first 12 months in the MA plan or PACE organization?
  8. Have you switched from a Medicare Supplement policy to a MA plan, PACE organization, Medicare SELECT plan, or any other health care organization contracting with Medicare, for the first time since becoming eligible for Medicare within the past 12 months?
  9. Has your MA plan left your area, and if so, did your MA plan benefits end within the past 123 days?

NOTE: Many people with Medicare Advantage plans who have serious health issues can still qualify for a guaranteed issue Medicare Supplement plan. See item #4 above.

What Insurance Carriers Do I Work With?

As a licensed independent insurance agent, I work with ALL the major insurance carriers in California. Most importantly, I WORK FOR YOU, not a particular insurance company! I’m also licensed in Arizona, Colorado, Nevada, and Washington state. Here are some, but not all, of the Medicare Supplement insurance carriers that I work with:

  • Aetna
  • Anthem Blue Cross
  • Blue Shield of California
  • Cigna
  • Health Net
  • Humana
  • Individual Assurance Company (IAC)
  • Mutual of Omaha
  • Oxford
  • Stonebridge
  • Transamerica
  • UnitedHealthcare (AARP)
  • United of Omaha

Let Me Do the Shopping For You!

While it is unusual for me to be able to save most of my clients over $5,300 per year on their annual insurance premiums like I did this past week, it is not unusual for me to give someone a free, no obligation quote and save them anywhere from $300 to $500 per year on their Medicare Supplement premiums. That happens quite frequently.

As an independent insurance agent, I have access to insurance quote engines and other information that is not available to the public. You should take advantage of my knowledge and experience and let me do the shopping for you to save you money on your insurance premiums.

grocery-shopping-cartIf you have a Medicare Supplement plan, please contact me for a free, no obligation quote. More than likely, I will save you hundreds of dollars on your Medicare Supplement insurance premiums.

As one of my clients, I will contact you every year, about a month before your birthday, and I will let you know what the best rates are at that time. You always have the option to either keep your current plan, or you can take advantage of the California Birthday Rule and change carriers if another company is offering better rates.

Either way, I strive to build trust and relationships with my clients. I will not do a magic act and disappear after you have your new policy, 😉 and you will always have the peace of mind knowing that you are not paying hundreds or even thousands of dollars more than you should be for your Medicare Supplement insurance.

If you have any questions, or if you or anyone that you know would like a free Medicare Supplement quote, please contact me at (760) 652-6060 or toll-free at (866) 718-1600. You can also reach me by email at Ron@RonLewisInsurance.com. Your questions and feedback are always welcome!