If you’re approaching age 65 or are already enrolled in Medicare, there’s something you should know about your annual doctor’s appointment: Medicare doesn’t cover a traditional annual physical examination.
This comes as a surprise to many people who have had employer-sponsored health insurance for years and are accustomed to scheduling a yearly physical with their doctor. After all, an annual checkup seems like one of the most basic healthcare benefits you would expect to have. The good news is that Medicare does provide coverage for preventive care through its Annual Wellness Visit. However, there are some important differences between a Medicare Wellness Visit and a traditional physical examination. Understanding those differences can help you avoid unexpected medical bills.
What Is a Medicare Annual Wellness Visit?
Medicare Part B covers an Annual Wellness Visit (AWV) once every 12 months for eligible beneficiaries. The purpose of this visit is to help you and your doctor develop a personalized prevention plan based on your health, medical history, and potential risk factors. Unlike a traditional physical, the Wellness Visit is primarily focused on reviewing your overall health and identifying potential health concerns before they become more serious.
During your appointment, your healthcare provider will review your medical and family history, update your list of medications and healthcare providers, check basic measurements such as your height, weight, and blood pressure, and assess certain health risks, including depression, cognitive impairment, and falls. Your provider may also discuss recommended preventive screenings and vaccinations, review lifestyle habits, and develop a personalized preventive care plan to help you maintain your health.
When you receive this covered service from a healthcare provider who accepts Medicare assignment, there is generally no out-of-pocket cost, provided the visit meets Medicare’s coverage requirements.
What does it mean when a doctor accepts Medicare assignment?
It means the doctor agrees to accept the Medicare-approved amount as full payment for covered services. The doctor cannot charge you more than the Medicare-approved amount for those services, although applicable deductibles, coinsurance, or copayments may still apply. If you have a Medicare Supplement Plan G and have already met your annual Part B deductible, your policy generally covers the remaining Medicare-approved Part B cost-sharing.
How Is a Medicare Wellness Visit Different From an Annual Physical?
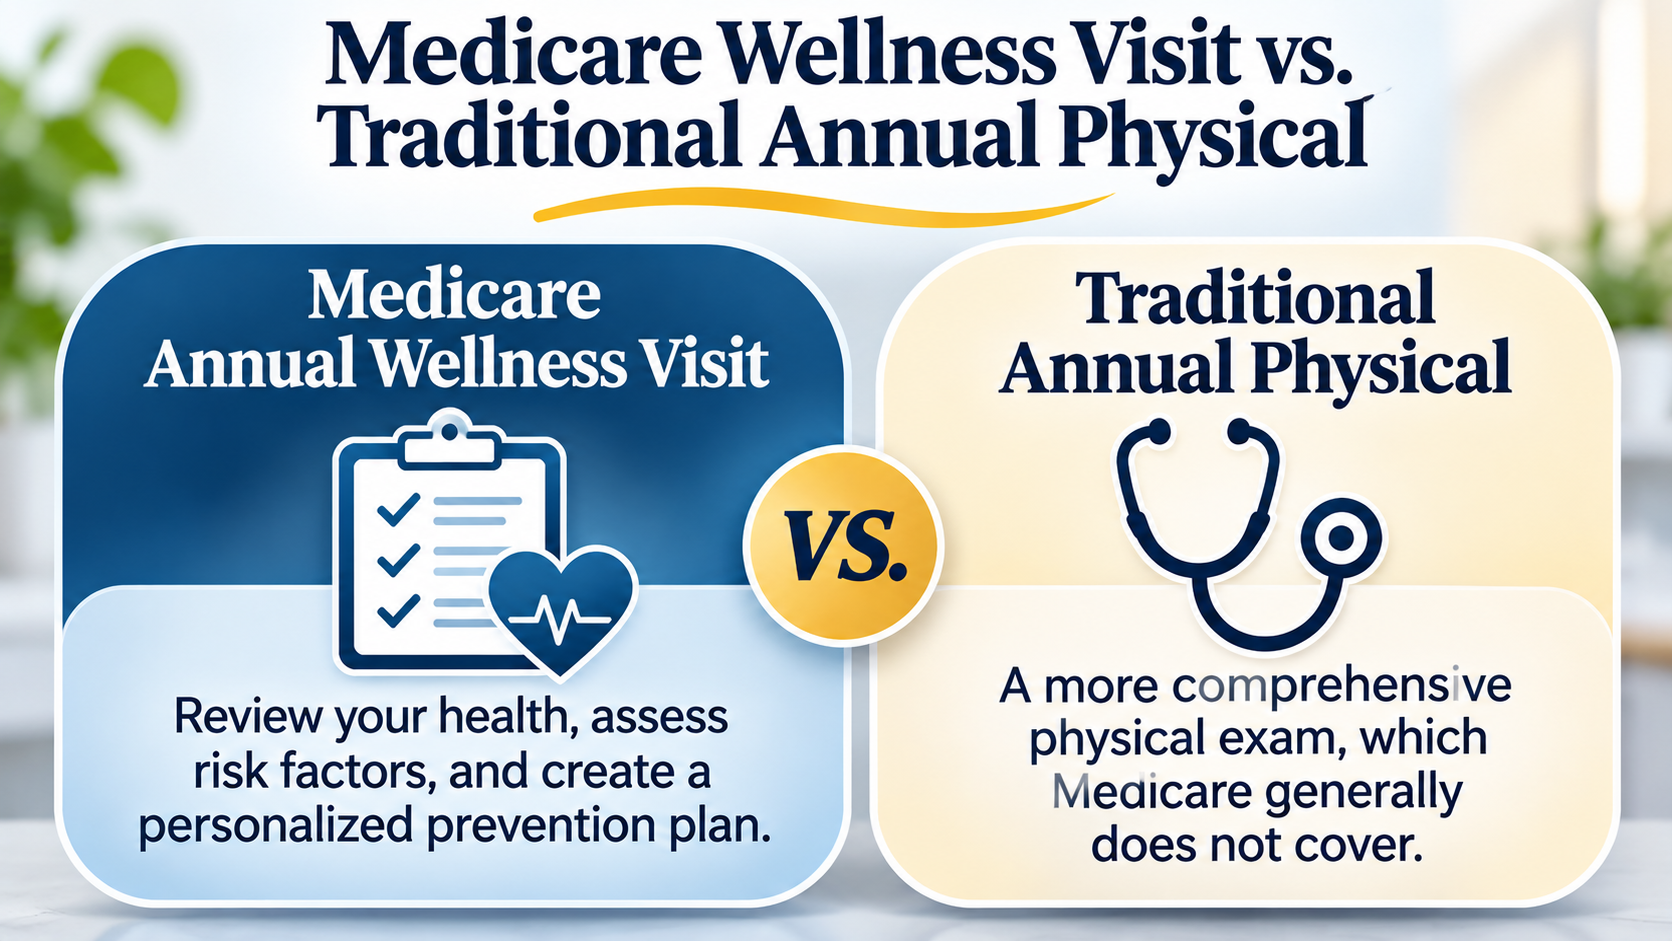
This is where the confusion often begins. Many people assume that a Medicare Wellness Visit is simply another name for the annual physical they’ve received throughout their lives. Unfortunately, that’s not the case.
A traditional physical examination typically involves a more hands-on assessment of your overall health. Your doctor may listen to your heart and lungs, examine your abdomen, check your ears and throat, and perform other examinations based on your age and medical history. Depending on your individual circumstances, the appointment may also include additional testing or laboratory work.
A Medicare Annual Wellness Visit generally does not include this type of comprehensive physical examination. Instead, its primary purpose is to assess your health risks, review your preventive care needs, and establish a plan to help you stay healthy. While both appointments are intended to support your overall well-being, they serve different purposes.
Does Medicare Pay for a Traditional Annual Physical?
Generally, no. Original Medicare does not cover routine physical examinations simply because you want an annual checkup. You can certainly schedule a traditional physical with your doctor after enrolling in Medicare, but you may be responsible for the entire cost of the examination.
It’s important to understand this distinction before making your appointment. If you specifically want a traditional physical, ask your doctor’s office whether Medicare covers the services being performed and what your estimated out-of-pocket cost will be. Also, keep in mind that if your doctor identifies or addresses a separate medical condition during your Medicare Wellness Visit, those additional services may be billed separately. If the services are covered by Medicare, your Medicare Supplement policy may help cover the associated out-of-pocket expenses, depending on your plan. However, if Medicare doesn’t cover the services, you may be responsible for the cost.
What About the Welcome to Medicare Visit?
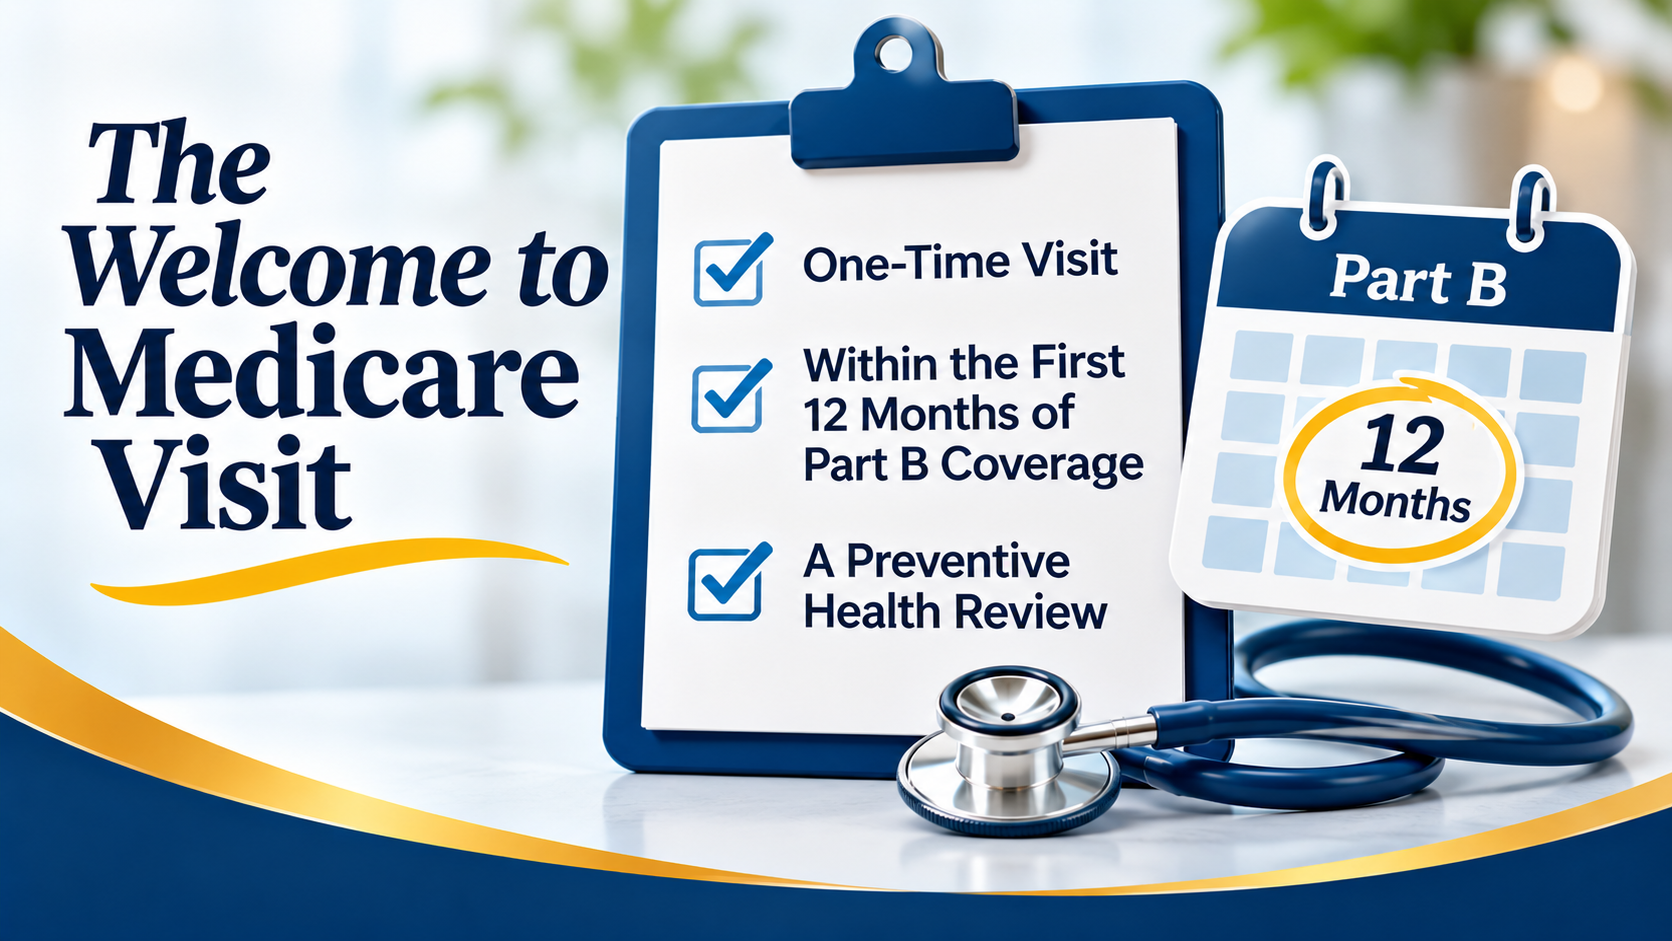
Medicare offers another preventive benefit when you first enroll in Part B. It’s called the Initial Preventive Physical Examination (IPPE), commonly referred to as the Welcome to Medicare visit. This is a one-time preventive appointment that must take place within the first 12 months of your Medicare Part B coverage.
The visit generally includes a review of your medical history, certain basic measurements, an assessment of potential health risks, and recommendations for preventive services. Despite its name, it is not a comprehensive physical examination either. If you receive this service from a provider who accepts Medicare assignment and meet the coverage requirements, there is generally no cost to you.
Does Having Medicare Supplement Plan G Make a Difference?
This is another question worth addressing, particularly if you have Original Medicare with a Medicare Supplement policy.
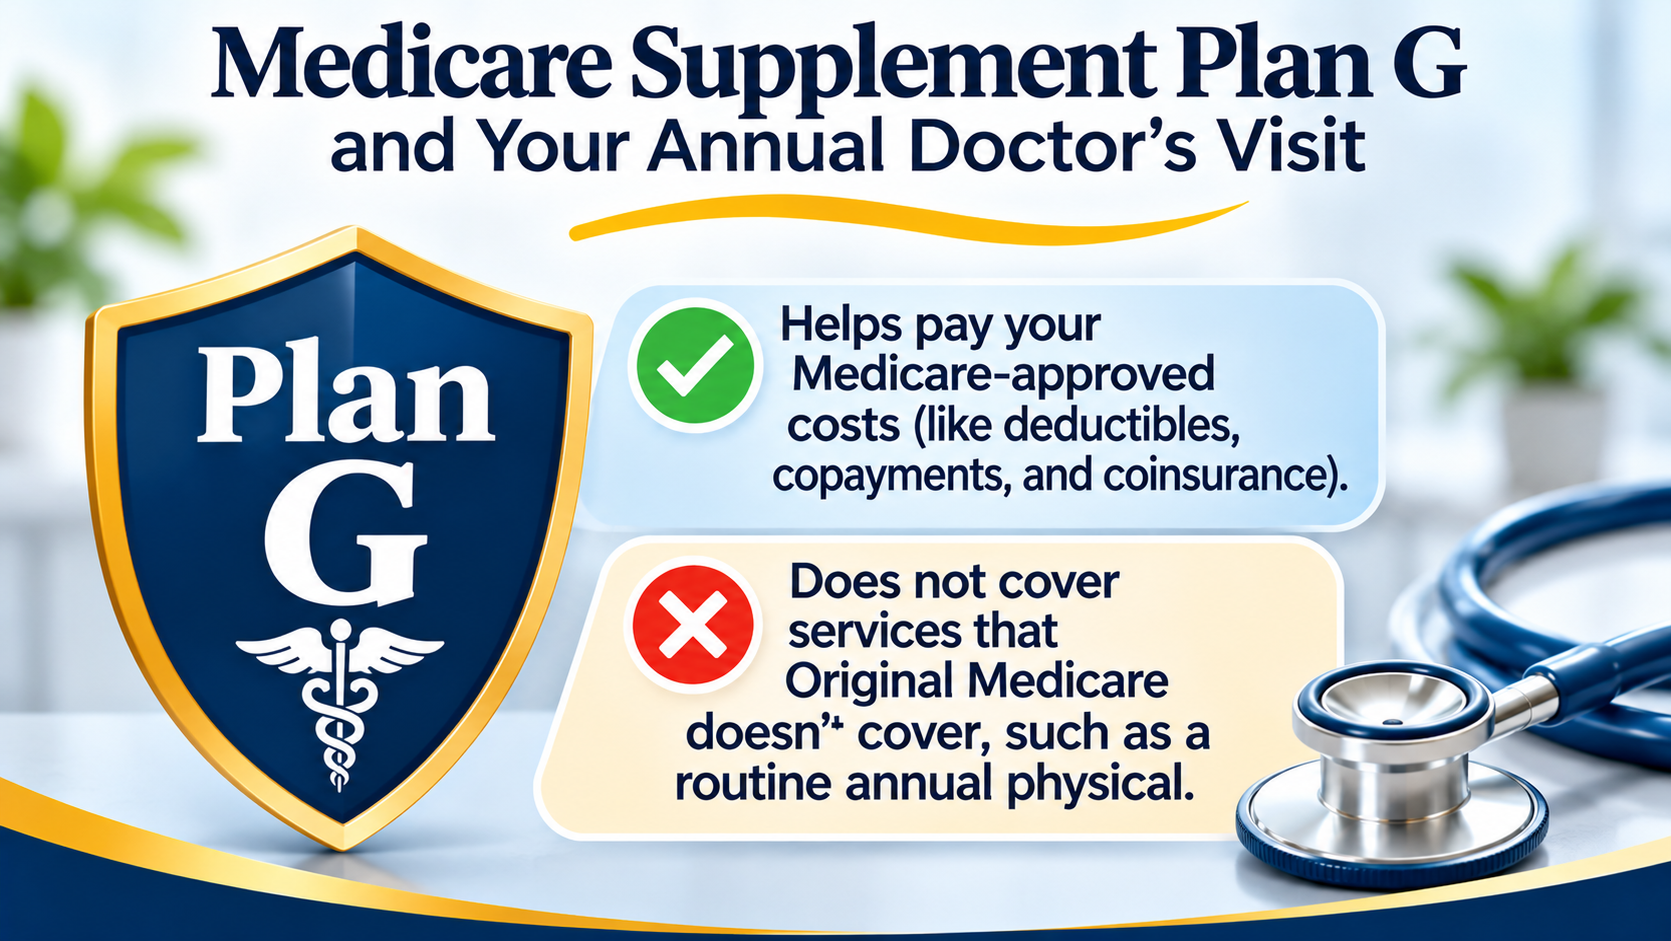
Medicare Supplement insurance, also known as Medigap, is designed to help pay certain out-of-pocket expenses associated with Original Medicare, such as deductibles, copayments, and coinsurance. For example, Medicare Supplement Plan G covers most Medicare-approved Part A and Part B cost-sharing expenses after you satisfy the annual Medicare Part B deductible.
However, having a Medicare Supplement policy does not mean that every medical service is covered. Since Original Medicare generally does not cover routine annual physical examinations, a Medicare Supplement policy does not provide coverage for an examination that Medicare excludes. In other words, even if you have one of the most comprehensive Medicare Supplement plans available, such as Plan G, you should not assume that a traditional annual physical will be covered.
What If You Have a Medicare Advantage Plan?
Medicare Advantage plans work somewhat differently. These plans are offered by private insurance companies and must provide at least the same Medicare-covered benefits as Original Medicare. They cover the Medicare Annual Wellness Visit, but some plans may also offer additional preventive benefits, including routine physical examinations.
Because benefits vary from one plan to another, it’s important to review your specific plan’s coverage rather than assume that every Medicare Advantage plan offers the same benefits. This is another example of why comparing Medicare Advantage and Medicare Supplement coverage involves more than simply comparing monthly premiums.
The Bottom Line: Know What Your Medicare Coverage Includes
One of the biggest adjustments when transitioning to Medicare is understanding that some of the healthcare benefits you’ve become accustomed to may work differently. Medicare provides excellent preventive care benefits, including its Annual Wellness Visit, but it’s important to understand that a Wellness Visit is not the same as a traditional annual physical.
Whether you have Original Medicare with a Medicare Supplement policy or a Medicare Advantage plan, take the time to understand your preventive care benefits before scheduling appointments. A little knowledge ahead of time can help you avoid unexpected medical bills.
If you’re approaching age 65, recently enrolled in Medicare, or simply have questions about how your current coverage works, I’m always happy to help you better understand your options. Understanding your Medicare coverage is an important part of making informed healthcare decisions.
About the Author
I’m an independent Medicare Supplement insurance specialist working with most of the major insurance carriers throughout California, Nevada, and Arizona.
I help people turning 65 coordinate their Medicare enrollment so their Medicare Supplement and prescription drug coverage begin at the same time as Medicare.
I also work with many people who already have Medicare Supplement plans and would like to review their options. In California, there is a law called the California Birthday Rule, which allows Medicare Supplement policyholders to change their plans each year during the 60 days following their birthday without answering health questions or going through medical underwriting. During this annual 60-day enrollment period, you cannot be turned down for coverage when changing to a Medicare Supplement plan with the same or fewer benefits.
I regularly help clients lower their Medicare Supplement premiums while keeping the same benefits and coverage.
Over the years, I have helped many clients save hundreds and sometimes even thousands of dollars on their annual premiums.
There is never a fee for my services because I am compensated by the insurance companies, not my clients. My goal is to help you find competitive premiums while providing dependable, personal service year after year.
If you’re turning 65 or already have a Medicare Supplement plan and would like to review your options, I’m happy to help.
Read what my clients have to say about working with me.
Contact Information
Ron Lewis
Independent Medicare Supplement Insurance Specialist
Cell: (760) 525-5769
Toll-Free: (866) 718-1600
Email: Ron@RonlewisInsurance.com
Website: www.MedigapShopper.com
Insurance Licenses
- California: #0B33674
- Nevada: #3822123
- Arizona: #681166
This website is operated by a licensed insurance agent and is intended for educational purposes only. I am not affiliated with or endorsed by Medicare or any government agency

