The 2026 Medicare Annual Election Period (AEP), is almost here. Beginning October 15 and ending December 7, 2026, Medicare beneficiaries will have an opportunity to review their Medicare coverage and make certain changes for the coming year. Changes made during this period generally take effect January 1, 2027.
You may hear quite a bit about AEP during the next few months. You will probably see television commercials, receive mail and phone calls from insurance companies and agents, and hear advertisements encouraging you to review your Medicare coverage.
With all of that information coming at you, I think it is important to understand what AEP actually means and, just as importantly, what it does not mean.
What Can You Change During AEP?
The Medicare Annual Election Period is an important time to review Medicare Advantage and Medicare Part D prescription drug coverage.
If you currently have a Medicare Advantage plan, AEP gives you an opportunity to review your coverage for 2027. You can stay with your current plan or, if you decide another option is better for you, make a change during the enrollment period.
If you have a Medicare Part D prescription drug plan, AEP is also an important time to review your coverage. Part D plans can change from year to year, including premiums, deductibles, copayments, covered medications and pharmacy networks. A plan that worked well for you in 2026 may not necessarily be the best option for you in 2027.
The important thing to remember is that you do not have to change your coverage simply because AEP arrives. AEP gives you an opportunity to review your options and make a change if you decide one is appropriate for you.
What About Medicare Supplement Plans?
This is where there is often some confusion. The Annual Election Period is not an annual open enrollment period for Medicare Supplement insurance. If you have a Medicare Supplement, also known as Medigap, you do not have to make a change to your Supplement simply because AEP is here. Medicare Supplement rules are different from Medicare Advantage and Part D.
California
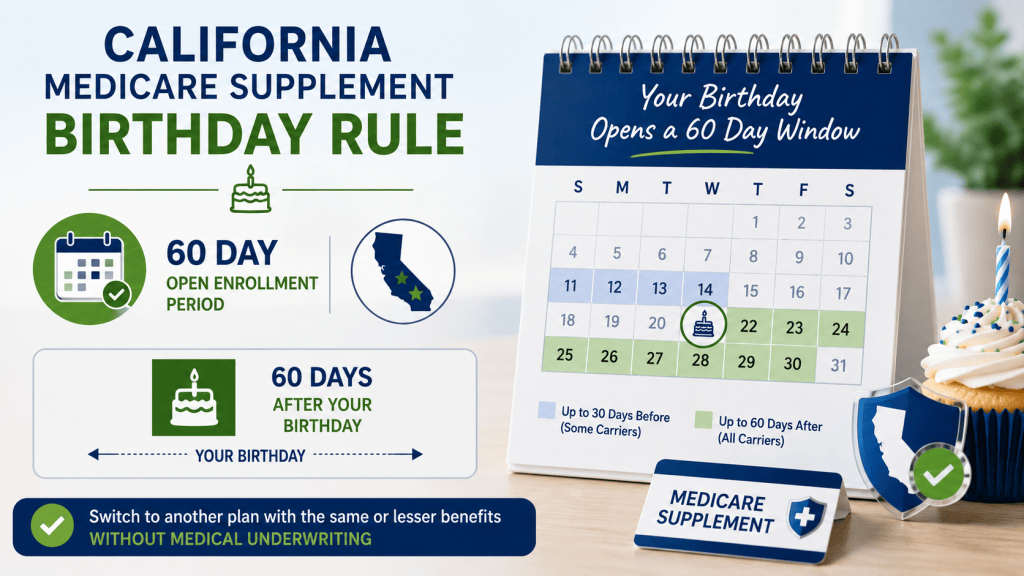
For my clients in California, there is another important time of year to be aware of. California has what is commonly called the Medicare Supplement Birthday Rule. If you already have a Medicare Supplement, you have a 60 day open enrollment period commencing with your birthday each year. During this period, you have the right to transfer to another Medicare Supplement plan with the same or lesser benefits without medical screening.
For example, if you currently have a Plan G, you could move to another Plan G or to a plan with lesser benefits, such as Plan N, during your Birthday Rule period without going through medical underwriting.
Your California Birthday Rule period is separate from the Medicare Annual Election Period. If you are happy with your Medicare Supplement, you do not need to make a change simply because AEP is here. Your birthday period provides a separate opportunity to review your Medicare Supplement options.
Nevada
For my clients in Nevada, there is also a Medicare Supplement Birthday Rule. Nevada Medicare Supplement policyholders have an annual open enrollment period beginning on the first day of their birthday month and extending for at least 60 days. During this period, they can purchase a new Medicare Supplement plan with the same or lesser benefits from either their existing insurance company or a different insurance company, without medical underwriting.
For example, if you currently have a Plan G, you could move to another Plan G or to a plan with lesser benefits, such as Plan N, during your Nevada Birthday Rule period without going through medical underwriting.
The Nevada Birthday Rule is also separate from the Medicare Annual Election Period. So, just as in California, AEP does not mean you need to make a change to your Medicare Supplement.
What If You Want to Switch From Medicare Supplement to Medicare Advantage?
If you currently have a Medicare Supplement and are considering switching to a Medicare Advantage plan, the Annual Election Period is one of the times when you can make that change, if you are eligible to enroll in a Medicare Advantage plan. However, this is a decision that deserves careful consideration.
One important thing to understand is that it can be easier to switch from a Medicare Supplement to Medicare Advantage than it can be to switch back to a Medicare Supplement later.
If you drop your Medicare Supplement to join a Medicare Advantage plan and later decide you want to return to Original Medicare, you may not be able to get your Medicare Supplement back without going through medical underwriting. Depending on your circumstances, you may have special rights to buy a Medicare Supplement, but those rights do not apply in every situation.
This is one of the reasons I believe you should think carefully before giving up a Medicare Supplement. Once you have a Medicare Supplement that you are comfortable with, it can be difficult to get comparable coverage again if your health changes.
If you are considering making this type of change, make sure you understand not only what the Medicare Advantage plan offers today, but also what your options would be if you later decide you want to return to Original Medicare and a Medicare Supplement.
If you have questions about your Medicare Supplement, that is something I am happy to help you with. My business is focused on Medicare Supplement insurance, and I am always glad to help my clients understand their Supplement coverage.
What If You Have a Part D Prescription Drug Plan?
If you have a Medicare Part D prescription drug plan, I recommend taking some time each year to review your coverage during AEP.
I do not sell Medicare Part D prescription drug plans, but I have created a separate guide specifically to help you with this process. It explains how to use Medicare’s Plan Finder to compare the Part D plans available in your area based on the medications you take and the pharmacy you use.
Medicare Part D Plans for 2027: How to Compare Your Options During AEP
In that guide, I explain how to compare your Part D options and what to look for when reviewing different plans.
If you’re wondering why I no longer sell Medicare Part D plans, I have also written an article explaining why some independent insurance agents, including myself, have stopped selling Medicare Advantage and Medicare Part D plans.
Why Some Insurance Agents Have Stopped Selling Medicare Advantage and Prescription Drug Plans
In that article, I explain some of the reasons behind my decision to focus my business on Medicare Supplement insurance rather than selling Medicare Advantage and Part D plans.
When Should You Start Reviewing Your Coverage?
Although AEP does not begin until October 15, you do not need to wait until then to start thinking about your coverage.
Medicare’s free 2026 handbook tells beneficiaries to begin comparing their current Medicare health or drug coverage with options for 2027 starting October 1. This gives you some time to review your choices before the Annual Election Period begins. You also do not need to wait until the last few days of AEP to make your decision. Giving yourself plenty of time can make the process less stressful and give you more time to ask questions if you need assistance.
AEP Does Not Mean You Have to Change Your Medicare Coverage
This is probably the most important thing I want you to remember. Every year during AEP, you will see advertisements encouraging you to review your Medicare coverage. While reviewing your coverage is a good idea, that does not mean you should automatically change plans.
If you have Medicare Advantage or Part D coverage, review your options and see whether another plan may be a better fit for you. You may find that your current plan is still the right choice.
If you have a Medicare Supplement, remember that AEP is not your annual Medicare Supplement open enrollment period. Your Medicare Supplement has its own rules, including the Birthday Rules in California and Nevada.
The goal is not to change your coverage simply because you can. The goal is to understand your options and make the decision that is right for you.
My Role During AEP
My business is focused on Medicare Supplement insurance. If you have questions about your Medicare Supplement, I am always happy to help you understand your coverage and your options.
For questions about Medicare Advantage or Part D prescription drug plans, I want to make sure you have access to information that allows you to consider the options available to you.
That is why I created my separate Part D guide. My goal is to give you a practical resource you can use when reviewing your prescription drug coverage.
A Final Reminder
The Medicare Annual Election Period runs from October 15 through December 7, 2026. If you have Medicare Advantage or Medicare Part D coverage, take some time to review your options for 2027.
If you have a Medicare Supplement, remember that AEP is not an annual open enrollment period for your Supplement. In California and Nevada, your Medicare Supplement has a separate Birthday Rule that provides an annual opportunity to review certain Supplement options.
Whether you decide to make a change or stay exactly where you are, the important thing is to understand your coverage and make an informed decision.
Disclaimer: This article is for educational purposes only and is not intended to provide individual insurance or financial advice. Medicare rules, benefits, costs and plan information can change. Always verify current information with Medicare or your state health insurance assistance program before making a Medicare coverage decision.
About the Author
I’m an independent Medicare Supplement insurance specialist working with most of the major insurance carriers throughout California, Nevada, Arizona, and several other states.
I help people turning 65 coordinate their Medicare enrollment so their Medicare Supplement and prescription drug coverage begin at the same time as Medicare.
I also work with many people who already have Medicare Supplement plans and would like to review their options. In California, there is a law called the California Birthday Rule, which allows Medicare Supplement policyholders to change their plans each year during the 60 days following their birthday without answering health questions or going through medical underwriting. During this annual 60 day enrollment period, you cannot be turned down for coverage when changing to a Medicare Supplement plan with the same or fewer benefits.
I regularly help clients lower their Medicare Supplement premiums while keeping the same benefits and coverage.
Over the years, I have helped many clients save hundreds and sometimes even thousands of dollars on their annual premiums.
There is never a fee for my services as I am compensated by the insurance companies, not my clients. My goal is to help you find competitive premiums while providing dependable, personal service year after year.
If you’re turning 65 or already have a Medicare Supplement plan and would like to review your options, I’m happy to help.
Read what my clients have to say about working with me.
Contact Information
Ron Lewis
Independent Medicare Supplement Insurance Specialist
Cell: (760) 525 5769
Toll Free: (866) 718 1600
Email: Ron@RonlewisInsurance.com
Website: www.MedigapShopper.com
Insurance Licenses
California: #0B33674
Nevada: #3822123
Arizona: #681166
This website is operated by a licensed insurance agent and is intended for educational purposes only. I am not affiliated with or endorsed by Medicare or any government agency.

