Understanding hospice coverage, Medicare Supplement insurance, and your options if you decide to pursue treatment again.
When someone receives a serious or terminal diagnosis, deciding whether to enter hospice care can be one of the most difficult decisions they and their family face. Hospice provides valuable support, including pain management, symptom relief, emotional support, and assistance for family caregivers. However, some people hesitate to choose hospice because they worry about losing access to medical treatment if their circumstances or preferences change.
If you have Original Medicare and a Medicare Supplement (Medigap) policy, it is important to understand how hospice affects your coverage and what options remain available to you.
What Is Medicare Hospice Care?
Hospice care is designed to provide comfort and support to people approaching the end of life. Rather than focusing on curing a terminal illness, hospice emphasizes pain relief, symptom management, and quality of life.
To qualify for the Medicare hospice benefit, a person generally must:
- Have Medicare Part A.
- Have a physician certify that they have a life expectancy of six months or less if their illness follows its normal course.
- Choose hospice care focused on comfort rather than treatment intended to cure the terminal illness and related conditions.
- Elect hospice through a Medicare-approved hospice provider.
The six-month prognosis is an eligibility guideline, not a guarantee of how long someone will live. People who live beyond six months may continue receiving hospice care if they remain eligible and meet the required recertification criteria.
Medicare Part A covers eligible hospice services, which may include nursing care, medications for symptom control, medical equipment, counseling, and support for family caregivers.
For more information, click here to access the Medicare hospice page.
What Happens to Original Medicare and Your Medicare Supplement When You Enter Hospice?
If you have Original Medicare (Part A and Part B) and a Medicare Supplement policy, electing hospice does not automatically cancel your Medicare coverage or your supplement. However, hospice election changes how Medicare covers treatment related to your terminal illness and certain related conditions.
For example, consider someone diagnosed with advanced cancer who chooses hospice care. While receiving the Medicare hospice benefit, the person generally will not have Medicare coverage for cancer treatment intended to cure the cancer outside the hospice arrangement. Instead, the hospice team focuses on comfort, pain relief, and managing symptoms. This does not mean that every treatment related to cancer is prohibited. Certain treatments may be provided or arranged by the hospice when they are part of the hospice plan of care. Medicare can also continue covering eligible medical care for conditions unrelated to the terminal illness.
What About Your Medicare Supplement?
Your Medicare Supplement policy remains in force as long as you maintain the policy and pay its premiums. However, Medicare Supplements do not cover any services not covered by Medicare. If Medicare does not cover a particular treatment because of the hospice election, your supplement will not cover the associated costs simply because you have Medigap insurance.
Different Medicare Supplement plans cover different amounts of Medicare cost-sharing, but the underlying hospice election rules generally apply regardless of which standardized Medigap plan you have. Keeping your Medicare Supplement does not mean every treatment will be covered while you are receiving hospice care.
Can You Change Your Mind After Choosing Hospice?
Yes. Medicare beneficiaries can revoke their hospice election at any time. Choosing hospice does not permanently eliminate the option of pursuing treatment again.
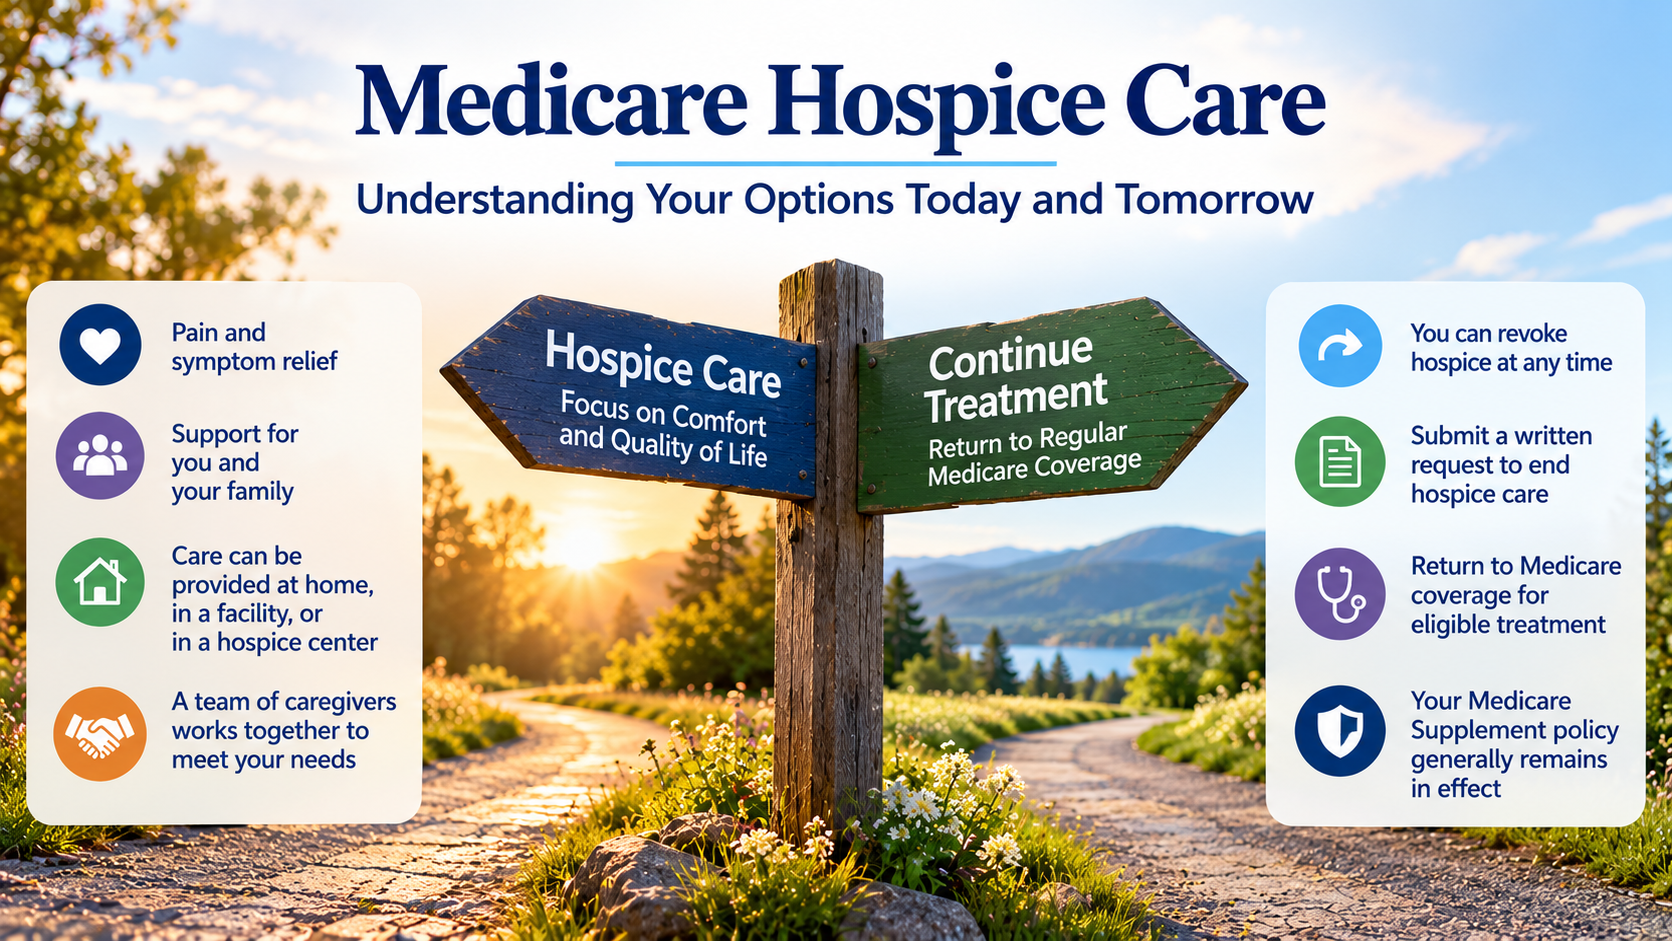
For example, imagine someone with cancer who initially decides to stop pursuing cancer-directed treatment and enter hospice. After several weeks, that person reconsiders and wants to explore additional treatment options with their oncologist. The person can revoke their hospice election and return to regular Medicare coverage for services that were previously waived because of the hospice election. If the cancer treatment meets Medicare’s usual coverage requirements, Medicare usually covers it, and the person does not need to wait until the original hospice election period ends to revoke hospice.
How Do You Revoke Hospice Care?
Revocation requires a written, signed statement submitted to the hospice provider. The statement must indicate that the person is revoking their hospice election and specify the effective date. The effective date cannot be earlier than the date the revocation is made. Simply telling the hospice team verbally is not sufficient.
Once the revocation takes effect, Medicare coverage of the benefits previously waived because of the hospice election resumes. The person gives up the remaining days in that particular hospice election period, but may elect hospice again later if eligible. Before making a change, discuss the decision with your treating physician and hospice team so you understand the medical implications and how your care will transition.
Does Leaving Hospice Guarantee Coverage for Every Treatment?
No. Revoking hospice restores access to regular Medicare coverage for services that were waived under the hospice election, but all ordinary Medicare coverage rules still apply.
For example, treatment must meet applicable Medicare coverage requirements. A particular procedure, medication, or therapy is not automatically covered simply because someone leaves hospice. Medicare Supplement insurance also follows the underlying Medicare coverage rules. It generally helps pay eligible Medicare cost-sharing rather than serving as separate, comprehensive health insurance. It is important to understand these distinctions before making decisions about hospice or treatment.
Questions to Ask Before Choosing Hospice
If you or a loved one is considering hospice, here are some useful questions to discuss with the treating physician and hospice provider:
- What treatments would be available under hospice, and which treatments would no longer be covered outside the hospice plan?
- Can the hospice provide or arrange treatments that may help control symptoms?
- Which medical services for unrelated conditions would continue to be covered?
- If I change my mind, what steps would I need to take to revoke my hospice election?
- How would leaving hospice affect my ongoing medical care and insurance costs?
Having these conversations can help you make an informed decision that reflects your medical needs, personal preferences, and goals for care.
The Bottom Line
Hospice can provide meaningful comfort and support to people facing a terminal illness. For many people, it is the right choice. Others may later decide they want to pursue additional treatment. If you have Original Medicare and a Medicare Supplement policy, choosing hospice does not automatically cancel your supplement or permanently eliminate your right to pursue treatment.
You can revoke your hospice election and return to regular Medicare coverage for eligible services that were previously waived. Your Medicare Supplement can continue to supplement covered Medicare services according to your policy’s terms. Understanding these options can help you and your family make informed decisions during a difficult time.
Important: This article is for educational purposes only and is not medical, legal, or individualized insurance advice. For questions about your specific coverage, consult Medicare, your hospice provider, and your insurance company.
About the Author
I’m an independent Medicare Supplement insurance specialist working with most of the major insurance carriers throughout California, Nevada, and Arizona.
I help people turning 65 coordinate their Medicare enrollment so their Medicare Supplement and prescription drug coverage begin at the same time as Medicare.
I also work with many people who already have Medicare Supplement plans and would like to review their options. In California, there is a law called the California Birthday Rule, which allows Medicare Supplement policyholders to change their plans each year during the 60 days following their birthday without answering health questions or going through medical underwriting. During this annual 60-day enrollment period, you cannot be turned down for coverage when changing to a Medicare Supplement plan with the same or fewer benefits.
I regularly help clients lower their Medicare Supplement premiums while keeping the same benefits and coverage.
Over the years, I have helped many clients save hundreds and sometimes even thousands of dollars on their annual premiums.
There is never a fee for my services because I am compensated by the insurance companies, not my clients. My goal is to help you find competitive premiums while providing dependable, personal service year after year.
If you’re turning 65 or already have a Medicare Supplement plan and would like to review your options, I’m happy to help.
Read what my clients have to say about working with me.
Contact Information
Ron Lewis
Independent Medicare Supplement Insurance Specialist
Cell: (760) 525-5769
Toll-Free: (866) 718-1600
Email: Ron@RonlewisInsurance.com
Website: www.MedigapShopper.com
Insurance Licenses
- California: #0B33674
- Nevada: #3822123
- Arizona: #681166
This website is operated by a licensed insurance agent and is intended for educational purposes only. I am not affiliated with or endorsed by Medicare or any government agency.

