Medicare Part D Plans for 2027: How to Compare Your Options During AEP

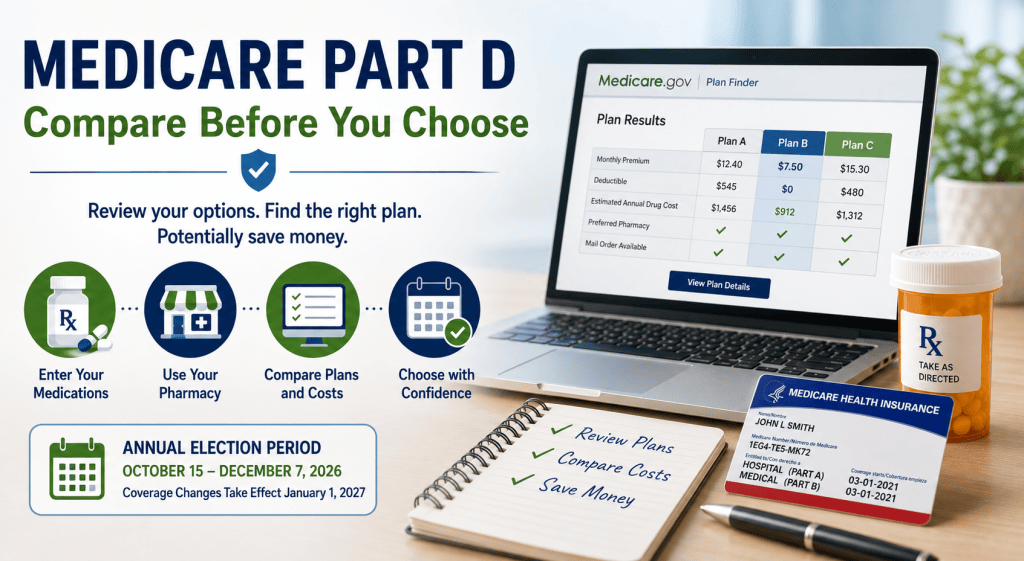
If you have a Medicare Part D prescription drug plan (PDP), the Medicare Annual Election Period (AEP) is an important time of year for you. The AEP runs from October 15 through December 7, 2026, and gives you an opportunity to review your Medicare Part D coverage and compare Medicare Part D plans for 2027.

Part D plans can change from year to year. Your premium, deductible, copayments, covered medications, pharmacy networks and other costs can change. Your own prescription needs may also change.

That is why I recommend reviewing your Part D coverage every year. You may discover that another plan could save you money or provide better coverage. You may also discover that your current plan is still the best choice. Either way, it is worth taking the time to check.

I Do Not Sell Medicare Part D Plans

Before I explain how to compare Part D plans, I want to be clear about something. I do not sell Medicare Part D prescription drug plans.

I have made a deliberate decision to specialize in Medicare Supplement insurance rather than sell Medicare Part D prescription drug plans. Selling and servicing Part D plans involves additional federal requirements, annual certification and training, as well as separate requirements for each insurance company whose Part D plans an agent represents.

After considering those requirements and what is involved in properly servicing Part D clients, I decided that I would rather focus my business on Medicare Supplement insurance and do that very well.

There is another important reason I believe this is a good approach for my clients. An insurance agent who sells Part D plans can only offer the plans from the insurance companies they are authorized and certified to represent. An agent may represent several companies, but may not represent every Part D plan available in your area.

Rather than have you choose a PDP from a limited selection of plans that I might represent, I would rather show you how to use Medicare’s Plan Finder to compare the plans available to you based on your own medications and pharmacy.

Don’t Choose a Plan Based Only on the Monthly Premium

One of the most important things to remember when comparing Part D plans is that the plan with the lowest monthly premium is not necessarily the plan that will cost you the least over the entire year. Your total prescription costs depend on several factors, including the medications you take, the dosage, the pharmacy you use and the plan’s deductible, copayments and coinsurance.

Medicare’s prescription drug plan comparison tool allows you to enter your actual medications and preferred pharmacy so that you can compare the plans based on your own situation. That is much more useful than simply asking someone which insurance company has the cheapest Part D plan because the plan with the lowest premium may not be the plan with the lowest overall cost for your particular medications.

NOTE: When you use the Medicare Plan Finder for your prescriptions, you can enter up to five pharmacies. I always enter five different pharmacies because you’ll find that depending on your PDP, certain pharmacies are “in network” and cost less than others, so the pharmacy you go to can affect the cost of your prescriptions.
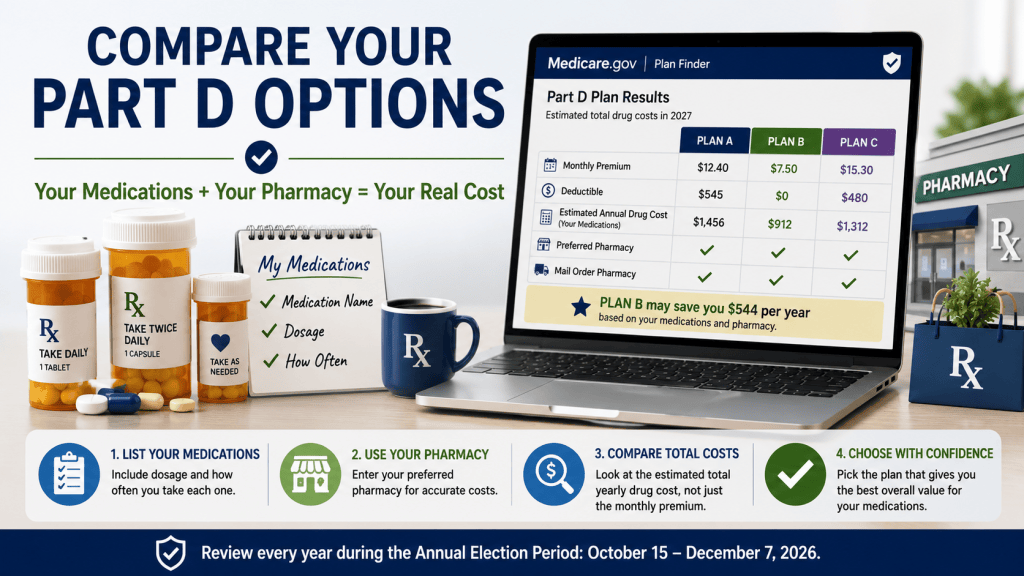
Comparing Medicare Part D plans for 2027 using Medicare Plan Finder

When Will the 2027 Medicare Part D Plans Be Available?

Medicare’s 2026 handbook tells beneficiaries to begin comparing their current Medicare health or drug coverage with options for 2027 starting October 1, 2026. The Medicare Plan Finder is expected to have the 2027 plan information available around that time, giving you an opportunity to review your options before the Annual Election Period begins on October 15.

Once the 2027 information is available, you can use Medicare’s Plan Finder to enter your medications and pharmacy and compare the Part D plans available in your area.

NOTE: You won’t be able to sign up for a new prescription drug plan until October 15, 2026. Again, the new coverage won’t go into effect until January 1st, 2027.

How to Use Medicare’s Plan Finder to Compare Part D Plans

The easiest way to compare Part D plans is to use Medicare’s official Plan Finder:

Medicare Plan Finder

When you use the Plan Finder, you first enter your zip code and then you can enter the medications you currently take, including the dosage and how frequently you take them. You can also enter the pharmacy you normally use. Medicare will then show you the Part D plans available in your area and estimate what you could pay based on the medications and pharmacy information you entered. Note that the prescription drug plans are sorted from cheapest to most expensive, depending on what prescriptions you are taking.

When comparing plans, don’t look only at the monthly premium. Look at the estimated total yearly cost, the deductible, your medication costs, the pharmacies available to you and any other differences that may affect what you actually pay throughout the year.

The Medicare Plan Finder is updated periodically, so the appearance and order of the information on the website may change a little. Don’t be concerned if the screens you see don’t look exactly like the ones shown in my video. The basic process of entering your medications, comparing plans and selecting a prescription drug plan remains the same.

I Created a Video Showing You How to Use Medicare’s Plan Finder

In 2025, I created a short video that walks you through the process of using Medicare.gov to enter your medications, compare your options, and enroll in a Part D plan.

2025 Video: How to Choose and Sign Up For a Prescription Drug Plan

Watch the 2025 Medicare Plan Finder Tutorial

Medicare has since made some changes to the appearance and layout of the Plan Finder tool. For example, some of the information appears in a different order than it did when I made my video. However, the basic process of using the Plan Finder to enter your medications, compare plans and select a prescription drug plan remains very similar.

Please keep in mind that the plan information shown in this video is from 2025 and should not be used to determine which plan you should choose for 2027. The purpose of the video is simply to show you how the Medicare Plan Finder works. Once the Medicare Plan Finder is updated with the information for 2027, I will create an updated video showing you the current process. I will let you know when the new video is available through my monthly newsletter.

What If You Need Help?

Not everyone is comfortable researching Medicare plans online, and that is completely understandable.

If you live in California, one resource I recommend becoming familiar with is the Health Insurance Counseling and Advocacy Program (HICAP), which provides free, confidential and unbiased Medicare counseling to California residents. HICAP counselors can help Medicare beneficiaries understand their Medicare options and answer questions about prescription drug coverage in person or on the phone.

California Health Insurance Counseling & Advocacy Program (HICAP)
https://www.shiphelp.org/ships/california/
1-800-434-0222

If you live in Nevada, you can contact the Nevada Medicare Assistance Program, commonly called MAP, for Medicare counseling and assistance.

Nevada Medicare Assistance Program (MAP)
https://www.shiphelp.org/ships/nevada/
1-800-307-4444

If you live outside of California or Nevada, you can find your local State Health Insurance Assistance Program (SHIP) through the national SHIP website.

Nationwide SHIP
State Health Insurance Assistance Program (SHIP)
https://www.shiphelp.org/
1-877-839-2675

These programs can be especially useful if you need help comparing Medicare options but do not want to rely on an insurance agent who may represent only certain insurance companies.

You Don’t Have to Change Plans

I want to emphasize one final point. Reviewing your Part D plan does not mean you have to change it.

You may compare the plans available for 2027 and discover that your current plan is still the best choice for you. If that happens, you can simply keep your current coverage. The important thing is that you take the time to check.

Prescription drug plans can change from year to year, and taking the time to review your options could potentially save you money or help you find coverage that better fits your needs.

My goal in writing this guide is not to tell you which Part D plan to choose. It is to give you the tools and information you need to make an informed decision for yourself.

My Recommendation for Comparing 2027 Part D Plans

If you currently have a Medicare Part D prescription drug plan, I recommend beginning to compare your current coverage with the 2027 plans as soon as the new plan information becomes available around October 1. Then, beginning October 15, you can make a change if you decide another plan is a better fit for you.

Enter your zip code, the actual medications and the pharmacy you normally use. Look at your estimated total yearly costs rather than simply choosing the plan with the lowest monthly premium. If your current plan still looks like the best option, stay with it. If another plan offers you better overall coverage and costs, you can make the change during the AEP.

How to Enroll in a Medicare Part D Plan

If you decide that you want to enroll in a new Medicare Part D plan, the easiest way to enroll is by clicking the Enroll button on the plan that you want to sign up with. You will need to provide your name, address, Medicare number, etc., but it normally takes less than 10 minutes to sign up that way. Otherwise, you can call the plan and enroll over the phone, but that generally takes longer.

IMPORTANT: If you have a Medicare Advantage plan that includes prescription drug coverage, be very careful about enrolling in a separate Medicare Part D prescription drug plan. In most cases, joining a separate Part D plan will automatically disenroll you from your Medicare Advantage plan and return you to Original Medicare. This could cause you to lose your Medicare Advantage health coverage and benefits. Before making any changes, make sure you understand how enrolling in a separate Part D plan will affect your current coverage.

Again, the AEP runs from October 15 through December 7, 2026. Take the time to review your coverage, compare your options, and make the decision that is right for you.

Disclaimer: This article is for educational purposes only and is not intended to provide individual insurance or financial advice. Medicare rules, benefits, costs and plan information can change. Always verify current information with Medicare or your state health insurance assistance program before making a Medicare coverage decision.

About the Author
I’m an independent Medicare Supplement insurance specialist working with most of the major insurance carriers throughout California, Nevada, and Arizona.

I help people turning 65 coordinate their Medicare enrollment so their Medicare Supplement and prescription drug coverage begin at the same time as Medicare.

I also work with many people who already have Medicare Supplement plans and would like to review their options. In California, there is a law called the California Birthday Rule, which allows Medicare Supplement policyholders to change their plans each year during the 60 days following their birthday without answering health questions or going through medical underwriting. During this annual 60-day enrollment period, you cannot be turned down for coverage when changing to a Medicare Supplement plan with the same or fewer benefits.

I regularly help clients lower their Medicare Supplement premiums while keeping the same benefits and coverage.

Over the years, I have helped many clients save hundreds and sometimes even thousands of dollars on their annual premiums.

There is never a fee for my services because I am compensated by the insurance companies, not my clients. My goal is to help you find competitive premiums while providing dependable, personal service year after year.

If you’re turning 65 or already have a Medicare Supplement plan and would like to review your options, I’m happy to help.

Read what my clients have to say about working with me.

Contact Information

Ron Lewis
Independent Medicare Supplement Insurance Specialist

Cell: (760) 525-5769

Toll-Free: (866) 718-1600

Email: Ron@RonlewisInsurance.com

Website: www.MedigapShopper.com

Insurance Licenses

  • California: #0B33674
  • Nevada: #3822123
  • Arizona: #681166

This website is operated by a licensed insurance agent and is intended for educational purposes only. I am not affiliated with or endorsed by Medicare or any government agency.
Why Some Insurance Agents Stopped Selling Medicare Advantage and Part D

Why some insurance agents no longer sell Medicare Advantage and Part D plans

If you have noticed that some insurance agents no longer offer Medicare Advantage or Medicare Part D plans, you are not imagining it.

Over the past several years, the rules governing the marketing and sale of Medicare Advantage and Part D plans have become increasingly detailed. Agents and brokers who sell these plans must meet annual training and testing requirements, follow Medicare marketing rules, comply with requirements imposed by the insurance companies they represent, and maintain appropriate documentation.

For some independent agents, the additional time, expense and responsibility have made these products less attractive to sell. I am one of those agents. I have made the decision to focus my business primarily on Medicare Supplement insurance rather than selling Medicare Advantage and Part D plans.

This does not mean that Medicare Advantage or Part D plans are bad coverage. These plans can be a good fit for many people. It simply means that I believe I can provide better service by specializing in Medicare Supplement insurance rather than trying to sell every type of Medicare product.

Why Have the Rules Become More Complicated?

Medicare Advantage and Part D plans are regulated by the Centers for Medicare & Medicaid Services, commonly called CMS.

CMS has established detailed requirements governing how these plans can be marketed and sold. The requirements are designed to protect Medicare beneficiaries and help ensure that people receive accurate information when making important coverage decisions.

Agents who sell Medicare Advantage and Part D plans must complete annual training and testing covering Medicare rules, regulations and the specific products they sell. Insurance companies and other organizations that work with agents also have their own certification and compliance requirements. For an independent agent who wants to represent multiple insurance companies, keeping up with all of these requirements can take a substantial amount of time.

Call Recording Adds Another Layer of Compliance

One of the requirements that has received considerable attention is the recording of certain calls involving Medicare Advantage and Part D sales and enrollment activities.

CMS requires organizations and individuals who meet the definition of a Third Party Marketing Organization, or TPMO, to record marketing, sales and enrollment calls in their entirety. Calls that do not involve marketing, sales or enrollment activities do not have to be recorded under this requirement.

This is an important distinction because the requirement is not simply that an agent must record every telephone conversation with every client. However, when an independent agent is conducting activities that fall under the Medicare marketing and enrollment rules, the recording and recordkeeping requirements can add another layer of technology, administration and compliance responsibility.

For a large organization or call center, these systems may be relatively easy to manage. For a small independent insurance practice, they can be much more burdensome.

Annual Training and Certification Take Time

Selling Medicare Advantage and Part D plans also requires ongoing training and testing. CMS requires agents and brokers who sell Medicare products to complete annual training and testing on Medicare rules and regulations as well as the specific benefits of the plans they sell.

An independent agent who represents several insurance companies may also need to complete separate certification requirements for those companies. That means an agent who wants to offer a broad selection of Medicare Advantage and Part D plans has to invest considerable time each year simply to remain qualified to sell and service those products.

There is nothing wrong with these requirements. In fact, I believe it is important that anyone helping a Medicare beneficiary choose coverage understand the products and the rules. The question for an independent agent is whether the time and resources required to remain active in this part of the business make sense for the practice.

Compensation Is Only One Part of the Equation

Compensation is another consideration, although it is not the only reason some agents have left this part of the Medicare business. CMS publishes compensation information for Medicare Advantage and Part D plans. Generally, independent agents receive an initial payment when a beneficiary enrolls and a lower renewal payment in subsequent years when applicable.

The amount an agent receives can vary depending on the type of enrollment, the plan, the state and other factors. For an independent agent, however, compensation has to be considered together with the time required for training, certification, compliance, documentation, technology and ongoing client service. An agent may decide that the overall economics simply do not make sense for the way he or she wants to operate a business. That is one of the reasons I decided to focus my practice on Medicare Supplement insurance.

Why I Chose to Specialize in Medicare Supplement Insurance

My decision is not based on the belief that Medicare Advantage or Part D plans are inherently bad. It is based on the type of service I want to provide.

As an independent Medicare Supplement insurance specialist, I can focus my time on helping clients compare Medicare Supplement plans from the insurance companies I represent. I can help clients compare premiums, benefits and other factors that are important when choosing a Medicare Supplement.

I also work with people who already have Medicare Supplement coverage and want to see whether they may be able to reduce their premiums while keeping the same benefits. That specialization allows me to concentrate on one area of Medicare rather than trying to be an expert in every type of Medicare insurance product.

There Is Another Important Consideration for Consumers

There is also a practical reason why I believe consumers should understand why some agents do not sell every Medicare plan available in their area. An insurance agent can generally only sell or enroll a beneficiary in the Medicare Advantage and Part D plans that the agent is properly licensed, appointed and certified to represent. That means an agent may represent several insurance companies but still not represent every Medicare Advantage or Part D plan available in a particular ZIP code. This does not necessarily mean the agent is doing anything wrong. It is simply a limitation that consumers should understand.

If you ask an agent to help you choose a Part D plan, for example, you may not necessarily be comparing every Part D plan available to you. That is one reason I created my separate guide explaining how to use Medicare’s Plan Finder.

How I Recommend Comparing Part D Plans

Because I do not sell Part D plans, I do not have a financial interest in recommending one Part D plan over another. Instead, I recommend using Medicare’s official Plan Finder to compare the plans available in your area based on your actual medications and the pharmacy you use.

For 2027, I have created a separate guide that walks through this process:

Medicare Part D Plans for 2027: How to Compare Your Options During AEP

The important thing is to compare the plans using your own prescriptions and pharmacy information rather than choosing a plan simply because it has the lowest monthly premium. A plan with a slightly higher premium could potentially have lower overall prescription costs for your particular medications.

What About Medicare Advantage Plans?

The same general principle applies to Medicare Advantage plans. Medicare Advantage plans can be a good choice for some beneficiaries, but they are different from Original Medicare combined with a Medicare Supplement.

If you are considering a Medicare Advantage plan, it is important to look at the plan’s provider network, prescription drug coverage, costs, rules for seeing specialists, prior authorization requirements and maximum out of pocket costs. You should also consider whether your doctors, hospitals and other providers participate in the plan.

Medicare Advantage plans can change from year to year, which is why reviewing your coverage during the Annual Election Period is important. However, reviewing your options does not automatically mean you should change plans.

Why I Am Comfortable Not Selling These Plans

Some people have asked me why I do not simply maintain appointments with more insurance companies so I can sell Medicare Advantage and Part D plans again.

For me, it comes down to specialization. I would rather focus my time on Medicare Supplement insurance and provide personal service to the clients I serve than spend a significant amount of time maintaining certifications and compliance requirements for products that are not the primary focus of my business.

I also believe consumers should know when an agent does not represent every plan available in their area. If I were helping someone select a Part D plan, for example, I would not want that person to assume that the plans I could offer represented every available option. That is why I would rather point people toward Medicare’s Plan Finder and show them how to compare the available plans for themselves.

What This Means for You During AEP

If you have Medicare Advantage or Medicare Part D coverage, you may notice that some agents who previously helped people with these plans are no longer doing so. That does not necessarily mean that those agents no longer care about their clients. For some independent agents, the combination of annual training, certification, compliance, documentation, call recording and other requirements has simply made these products less practical to offer.

At the same time, these requirements are intended to protect Medicare beneficiaries and promote accurate information when people are making important Medicare decisions. CMS continues to maintain detailed requirements for agents and brokers who sell Medicare Advantage and Part D plans.

If you need help reviewing your Part D coverage, you do not have to rely solely on an insurance agent. You can use Medicare’s Plan Finder to compare the plans available in your area, and you can also contact the California Health Insurance Counseling & Advocacy Program (HICAP) for free, unbiased Medicare counseling.

Here is their contact information:

California Health Insurance Counseling & Advocacy Program (HICAP)
https://www.shiphelp.org/ships/california/
1-800-434-0222

My Role as an Independent Medicare Supplement Specialist

My business is focused on Medicare Supplement insurance. I work with most of the major insurance carriers offering Medicare Supplement plans in the states where I am licensed. If you already have a Medicare Supplement, I can help you review your current premium and compare other available Medicare Supplement options. If you are turning 65, I can also help you coordinate your Medicare enrollment with your Medicare Supplement coverage.

For Medicare Advantage and Part D plans, my goal is different. I want to make sure you have access to the information and tools you need to understand your options, even though I do not sell those plans. That is why I created my Part D guide and why I recommend using Medicare’s own Plan Finder when comparing prescription drug plans.

The Bottom Line

Medicare Advantage and Part D plans are important parts of the Medicare program, and they can be a good fit for many people. At the same time, the business of selling these plans has become more regulated and more complicated for independent insurance agents. Annual training and testing, carrier certifications, marketing requirements, documentation, call recording and other compliance responsibilities all require time and resources. For some agents, including me, the decision has been to focus on Medicare Supplement insurance instead.

If you have Medicare Advantage or Part D coverage, do not assume that you need to change plans simply because AEP arrives. Review your options, compare the coverage and costs that apply to your own situation, and make the decision that is right for you.

For more information about the 2026 Annual Election Period, see:

The 2026 Medicare Annual Election Period is Almost Here: What You Need to Know!

And if you have a Medicare Part D plan, see:

Medicare Part D Plans for 2027: How to Compare Your Options During AEP

Disclaimer: This article is for educational purposes only and is not intended to provide individual insurance, legal or financial advice. Medicare rules, benefits, costs and plan information can change. Always verify current information with Medicare or your State Health Insurance Assistance Program before making a Medicare coverage decision.

About the Author

I’m an independent Medicare Supplement insurance specialist working with most of the major insurance carriers throughout California, Nevada, and Arizona.

I help people turning 65 coordinate their Medicare enrollment so their Medicare Supplement and prescription drug coverage begin at the same time as Medicare.

I also work with many people who already have Medicare Supplement plans and would like to review their options. In California, there is a law called the California Birthday Rule, which allows Medicare Supplement policyholders to change their plans each year during the 60 days following their birthday without answering health questions or going through medical underwriting. During this annual 60-day open enrollment period, you cannot be turned down for coverage when changing to a Medicare Supplement plan with the same or fewer benefits.

I regularly help clients lower their Medicare Supplement premiums while keeping the same benefits and coverage.

Over the years, I have helped many clients save hundreds and sometimes even thousands of dollars on their annual premiums.

There is never a fee for my services because I am compensated by the insurance companies, not my clients. My goal is to help you find competitive premiums while providing dependable, personal service year after year.

If you’re turning 65 or already have a Medicare Supplement plan and would like to review your options, I’m happy to help.

Read what my clients have to say about working with me.

Contact Information

Ron Lewis
Independent Medicare Supplement Insurance Specialist

Cell: (760) 525-5769

Toll-Free: (866) 718-1600

Email: Ron@RonlewisInsurance.com

Website: www.MedigapShopper.com

Insurance Licenses

  • California: #0B33674
  • Nevada: #3822123
  • Arizona: #681166

This website is operated by a licensed insurance agent and is intended for educational purposes only. I am not affiliated with or endorsed by Medicare or any government agency.