Medicare Part D Plans for 2027: How to Compare Your Options During AEP

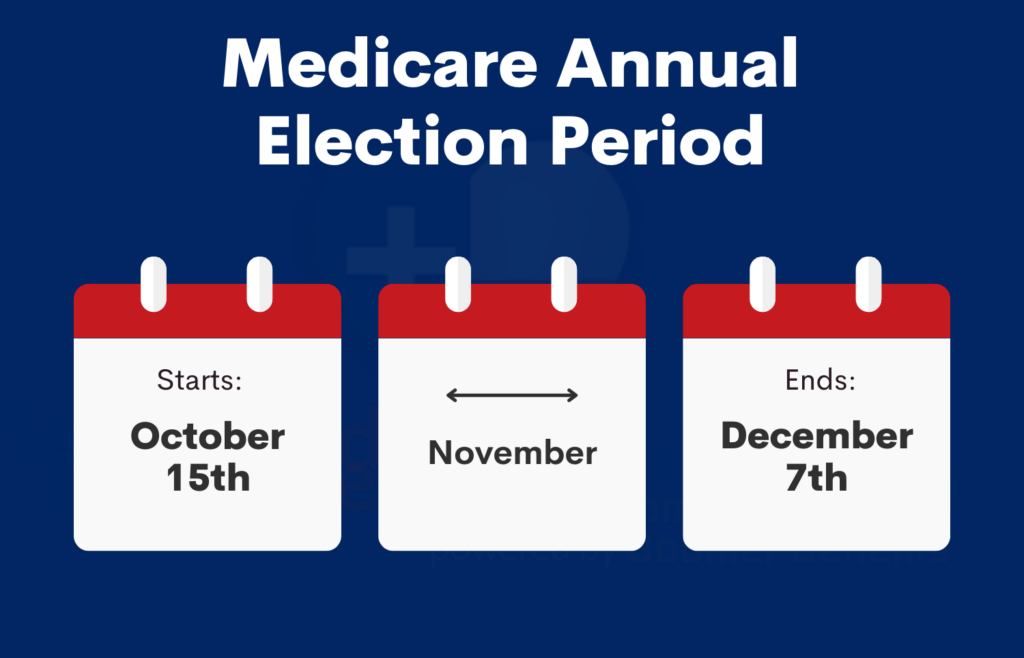
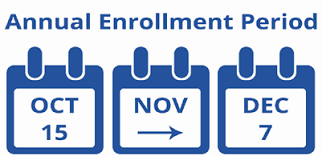
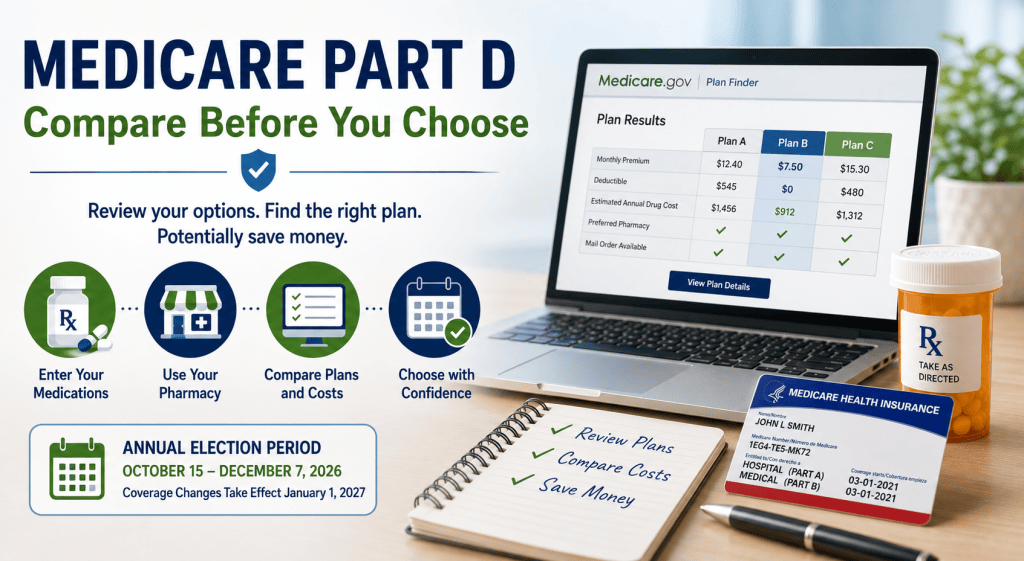
If you have a Medicare Part D prescription drug plan (PDP), the Medicare Annual Election Period (AEP) is an important time of year for you. The AEP runs from October 15 through December 7, 2026, and gives you an opportunity to review your Medicare Part D coverage and compare Medicare Part D plans for 2027.

Part D plans can change from year to year. Your premium, deductible, copayments, covered medications, pharmacy networks and other costs can change. Your own prescription needs may also change.

That is why I recommend reviewing your Part D coverage every year. You may discover that another plan could save you money or provide better coverage. You may also discover that your current plan is still the best choice. Either way, it is worth taking the time to check.

I Do Not Sell Medicare Part D Plans

Before I explain how to compare Part D plans, I want to be clear about something. I do not sell Medicare Part D prescription drug plans.

I have made a deliberate decision to specialize in Medicare Supplement insurance rather than sell Medicare Part D prescription drug plans. Selling and servicing Part D plans involves additional federal requirements, annual certification and training, as well as separate requirements for each insurance company whose Part D plans an agent represents.

After considering those requirements and what is involved in properly servicing Part D clients, I decided that I would rather focus my business on Medicare Supplement insurance and do that very well.

There is another important reason I believe this is a good approach for my clients. An insurance agent who sells Part D plans can only offer the plans from the insurance companies they are authorized and certified to represent. An agent may represent several companies, but may not represent every Part D plan available in your area.

Rather than have you choose a PDP from a limited selection of plans that I might represent, I would rather show you how to use Medicare’s Plan Finder to compare the plans available to you based on your own medications and pharmacy.

Don’t Choose a Plan Based Only on the Monthly Premium

One of the most important things to remember when comparing Part D plans is that the plan with the lowest monthly premium is not necessarily the plan that will cost you the least over the entire year. Your total prescription costs depend on several factors, including the medications you take, the dosage, the pharmacy you use and the plan’s deductible, copayments and coinsurance.

Medicare’s prescription drug plan comparison tool allows you to enter your actual medications and preferred pharmacy so that you can compare the plans based on your own situation. That is much more useful than simply asking someone which insurance company has the cheapest Part D plan because the plan with the lowest premium may not be the plan with the lowest overall cost for your particular medications.

NOTE: When you use the Medicare Plan Finder for your prescriptions, you can enter up to five pharmacies. I always enter five different pharmacies because you’ll find that depending on your PDP, certain pharmacies are “in network” and cost less than others, so the pharmacy you go to can affect the cost of your prescriptions.
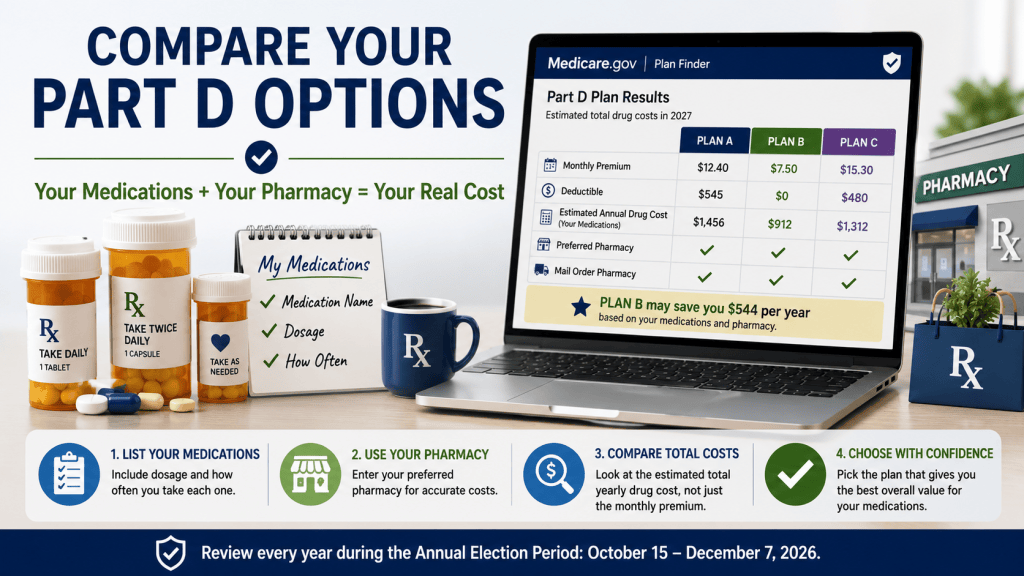
Comparing Medicare Part D plans for 2027 using Medicare Plan Finder

When Will the 2027 Medicare Part D Plans Be Available?

Medicare’s 2026 handbook tells beneficiaries to begin comparing their current Medicare health or drug coverage with options for 2027 starting October 1, 2026. The Medicare Plan Finder is expected to have the 2027 plan information available around that time, giving you an opportunity to review your options before the Annual Election Period begins on October 15.

Once the 2027 information is available, you can use Medicare’s Plan Finder to enter your medications and pharmacy and compare the Part D plans available in your area.

NOTE: You won’t be able to sign up for a new prescription drug plan until October 15, 2026. Again, the new coverage won’t go into effect until January 1st, 2027.

How to Use Medicare’s Plan Finder to Compare Part D Plans

The easiest way to compare Part D plans is to use Medicare’s official Plan Finder:

Medicare Plan Finder

When you use the Plan Finder, you first enter your zip code and then you can enter the medications you currently take, including the dosage and how frequently you take them. You can also enter the pharmacy you normally use. Medicare will then show you the Part D plans available in your area and estimate what you could pay based on the medications and pharmacy information you entered. Note that the prescription drug plans are sorted from cheapest to most expensive, depending on what prescriptions you are taking.

When comparing plans, don’t look only at the monthly premium. Look at the estimated total yearly cost, the deductible, your medication costs, the pharmacies available to you and any other differences that may affect what you actually pay throughout the year.

The Medicare Plan Finder is updated periodically, so the appearance and order of the information on the website may change a little. Don’t be concerned if the screens you see don’t look exactly like the ones shown in my video. The basic process of entering your medications, comparing plans and selecting a prescription drug plan remains the same.

I Created a Video Showing You How to Use Medicare’s Plan Finder

In 2025, I created a short video that walks you through the process of using Medicare.gov to enter your medications, compare your options, and enroll in a Part D plan.

2025 Video: How to Choose and Sign Up For a Prescription Drug Plan

Watch the 2025 Medicare Plan Finder Tutorial

Medicare has since made some changes to the appearance and layout of the Plan Finder tool. For example, some of the information appears in a different order than it did when I made my video. However, the basic process of using the Plan Finder to enter your medications, compare plans and select a prescription drug plan remains very similar.

Please keep in mind that the plan information shown in this video is from 2025 and should not be used to determine which plan you should choose for 2027. The purpose of the video is simply to show you how the Medicare Plan Finder works. Once the Medicare Plan Finder is updated with the information for 2027, I will create an updated video showing you the current process. I will let you know when the new video is available through my monthly newsletter.

What If You Need Help?

Not everyone is comfortable researching Medicare plans online, and that is completely understandable.

If you live in California, one resource I recommend becoming familiar with is the Health Insurance Counseling and Advocacy Program (HICAP), which provides free, confidential and unbiased Medicare counseling to California residents. HICAP counselors can help Medicare beneficiaries understand their Medicare options and answer questions about prescription drug coverage in person or on the phone.

California Health Insurance Counseling & Advocacy Program (HICAP)
https://www.shiphelp.org/ships/california/
1-800-434-0222

If you live in Nevada, you can contact the Nevada Medicare Assistance Program, commonly called MAP, for Medicare counseling and assistance.

Nevada Medicare Assistance Program (MAP)
https://www.shiphelp.org/ships/nevada/
1-800-307-4444

If you live outside of California or Nevada, you can find your local State Health Insurance Assistance Program (SHIP) through the national SHIP website.

Nationwide SHIP
State Health Insurance Assistance Program (SHIP)
https://www.shiphelp.org/
1-877-839-2675

These programs can be especially useful if you need help comparing Medicare options but do not want to rely on an insurance agent who may represent only certain insurance companies.

You Don’t Have to Change Plans

I want to emphasize one final point. Reviewing your Part D plan does not mean you have to change it.

You may compare the plans available for 2027 and discover that your current plan is still the best choice for you. If that happens, you can simply keep your current coverage. The important thing is that you take the time to check.

Prescription drug plans can change from year to year, and taking the time to review your options could potentially save you money or help you find coverage that better fits your needs.

My goal in writing this guide is not to tell you which Part D plan to choose. It is to give you the tools and information you need to make an informed decision for yourself.

My Recommendation for Comparing 2027 Part D Plans

If you currently have a Medicare Part D prescription drug plan, I recommend beginning to compare your current coverage with the 2027 plans as soon as the new plan information becomes available around October 1. Then, beginning October 15, you can make a change if you decide another plan is a better fit for you.

Enter your zip code, the actual medications and the pharmacy you normally use. Look at your estimated total yearly costs rather than simply choosing the plan with the lowest monthly premium. If your current plan still looks like the best option, stay with it. If another plan offers you better overall coverage and costs, you can make the change during the AEP.

How to Enroll in a Medicare Part D Plan

If you decide that you want to enroll in a new Medicare Part D plan, the easiest way to enroll is by clicking the Enroll button on the plan that you want to sign up with. You will need to provide your name, address, Medicare number, etc., but it normally takes less than 10 minutes to sign up that way. Otherwise, you can call the plan and enroll over the phone, but that generally takes longer.

IMPORTANT: If you have a Medicare Advantage plan that includes prescription drug coverage, be very careful about enrolling in a separate Medicare Part D prescription drug plan. In most cases, joining a separate Part D plan will automatically disenroll you from your Medicare Advantage plan and return you to Original Medicare. This could cause you to lose your Medicare Advantage health coverage and benefits. Before making any changes, make sure you understand how enrolling in a separate Part D plan will affect your current coverage.

Again, the AEP runs from October 15 through December 7, 2026. Take the time to review your coverage, compare your options, and make the decision that is right for you.

Disclaimer: This article is for educational purposes only and is not intended to provide individual insurance or financial advice. Medicare rules, benefits, costs and plan information can change. Always verify current information with Medicare or your state health insurance assistance program before making a Medicare coverage decision.

About the Author
I’m an independent Medicare Supplement insurance specialist working with most of the major insurance carriers throughout California, Nevada, and Arizona.

I help people turning 65 coordinate their Medicare enrollment so their Medicare Supplement and prescription drug coverage begin at the same time as Medicare.

I also work with many people who already have Medicare Supplement plans and would like to review their options. In California, there is a law called the California Birthday Rule, which allows Medicare Supplement policyholders to change their plans each year during the 60 days following their birthday without answering health questions or going through medical underwriting. During this annual 60-day enrollment period, you cannot be turned down for coverage when changing to a Medicare Supplement plan with the same or fewer benefits.

I regularly help clients lower their Medicare Supplement premiums while keeping the same benefits and coverage.

Over the years, I have helped many clients save hundreds and sometimes even thousands of dollars on their annual premiums.

There is never a fee for my services because I am compensated by the insurance companies, not my clients. My goal is to help you find competitive premiums while providing dependable, personal service year after year.

If you’re turning 65 or already have a Medicare Supplement plan and would like to review your options, I’m happy to help.

Read what my clients have to say about working with me.

Contact Information

Ron Lewis
Independent Medicare Supplement Insurance Specialist

Cell: (760) 525-5769

Toll-Free: (866) 718-1600

Email: Ron@RonlewisInsurance.com

Website: www.MedigapShopper.com

Insurance Licenses

  • California: #0B33674
  • Nevada: #3822123
  • Arizona: #681166

This website is operated by a licensed insurance agent and is intended for educational purposes only. I am not affiliated with or endorsed by Medicare or any government agency.

Why You Should Contact HICAP for Help Choosing a Medicare Prescription Drug Plan

Choosing a Medicare Prescription Drug Plan (PDP), which is also known as Part D, can feel overwhelming. With dozens of plans available, each with different premiums, deductibles, copays, and pharmacy networks, it’s easy to make a costly mistake.

As a Medicare Supplement (Medigap) insurance agent, I often get questions from clients who also want help selecting a Part D plan. While I’d love to help, I recently learned that helping someone choose or enroll in a Part D plan without proper certification could put my insurance license at risk. However, there’s a better option that is free, unbiased, and comprehensive through the Health Insurance Counseling and Advocacy Program (HICAP).

Many Insurance Agents Have Stopped Selling Prescription Drug Plans

If you’ve noticed that fewer independent agents are offering Medicare Prescription Drug (Part D) plans, you’re not imagining things. Over the past couple of years, the Centers for Medicare & Medicaid Services (CMS) has introduced an increasing number of onerous regulations that have made it extremely difficult for many agents to continue offering these plans, especially independent agents who value personal service and client relationships.

For example, CMS recently began requiring insurance agents to record every marketing, sales, and enrollment call related to Medicare Prescription Drug Plans (Part D). This means any discussion involving benefits, costs, or plan comparisons must be recorded, both inbound and outbound, and those recordings must be securely stored for 10 years. Agents don’t like this and many Medicare beneficiaries don’t want their conversations recorded.

While these rules were intended to protect consumers from misleading marketing, the burden of compliance has become overwhelming for many professionals in the field. For more detailed information, please click here to check out my other blog called “Why Many Insurance Agents Have Stopped Selling Prescription Drug and Advantage Plans,” and click here to to check out another related blog called “Why You May Be Better Off Choosing Your Own Medicare Prescription Drug Plan (Part D).”

Why an Insurance Agent Might Not Be Enough

Many insurance agents are only certified to sell PDP’s from certain insurance carriers, which means:

  • They may not have access to every plan available in your area.
  • Their guidance could be influenced by commissions or appointments, even unintentionally.
  • You may not get a complete picture of your options, which can lead to higher costs or gaps in coverage.

That’s where HICAP comes in.

What is HICAP and How It Helps

The Health Insurance Counseling and Advocacy Program (HICAP) is a free, state-run program in California that provides free, confidential one-on-one counseling, education, and assistance to individuals and their families on Medicare, Long-Term Care insurance, other health insurance related issues, and planning ahead for Long-Term Care needs.

HICAP also provides legal assistance or legal referrals in dealing with Medicare or Long-Term Care insurance related issues. HICAP counselors are trained in Medi-Cal and Medicare and can help you understand the complex insurance options to find the best fit for you.

HICAP counselors:

  • Can show all available Part D plans in your area.
  • Provide completely unbiased guidance, with no sales pressure.
  • Help you compare costs, deductibles, co-pays, and pharmacy networks.
  • Walk you through the Medicare Plan Finder tool or help you understand your plan options.

What HICAP Services Are Available?

HICAP can help you with the following:

  • Have questions on prescription drug coverage, co-pays, or eligibility rules?
  • Wondering how to sign up for Medicare now that you are almost 65?
  • Confused about all the different parts to Medicare, do you need A, B, C, D?
  • Need help filing an appeal or challenging a denial?
  • Considering long-term care insurance?
  • Need a speaker for a community education event?

How a HICAP Session Works

Whether over the phone or in person, the process is simple:

  • Prepare your information: Have a list of all your prescriptions, your preferred pharmacy, and your zip code.
  • Enter your own prescriptions: You input your medication information into Medicare.gov.
  • Guided support: The HICAP counselor explains your options, interprets plan details, and answers questions.
  • Compare plans: They help you see which plan offers the best coverage for your needs.
  • Enrollment: You complete the enrollment yourself online or by calling the plan.

Who Can Get These Services?

Counseling is provided to the following individuals:

  • Persons 65 years of age or older and are eligible for Medicare
  • Persons younger than age 65 years of age with a disability and are eligible for Medicare
  • Persons soon to be eligible for Medicare

Why HICAP is the Best Choice

HICAP counselors provide a full picture of your options, which an insurance agent cannot always do. Their guidance is independent, comprehensive, and free. This ensures you make an informed decision about your prescription coverage without missing important details or paying more than necessary.

Check Out My Video — How to Sign Up for a PDP on the Medicare Website

This past year, I created a step-by-step YouTube video that shows you how to use the Medicare Plan Finder tool. Nothing has changed since last year. Instead of contacting a HICAP counselor, you should be able to watch the video and be able to select a PDP and enroll on your own. It’s really very easy! Please click here to watch the video. It’s only 14 minutes long.

Next Steps

If you’re ready to compare Medicare Prescription Drug Plans for 2026:

  • Click here to watch my Youtube video that explains how to to use the Medicare Plan Finder tool to select a PDP and enroll on your own.
  • Call HICAP at 1-800-434-0222 or click here to find a local office in California.
  • In other states besides California, you can get help at your local State Health Insurance Assistance Program (SHIP). Their phone number is 1-877-839-2675 or click here to find a local office outside of California.

And if you have questions about Medicare Supplement (Medigap) plans, I’m here to help guide you through your options.

Conclusion

Choosing a Part D plan doesn’t have to be stressful. By using HICAP’s free, unbiased services, you can get all the information you need to make the best decision for your health and budget, while staying in control of the process.

About the Author

As an independent Medicare Supplement insurance specialist, I work with most of the major insurance carriers throughout California, Nevada, Arizona, and several other states. I shop around for my clients every year during their 60-day annual open enrollment period under the California Birthday Rule to help them save money on their Medicare Supplement premiums. Many of my clients have saved hundreds, even thousands of dollars on the same exact plan and coverage! Please click here to see what my clients have to say about my services.

There is no charge for my services as I’m compensated by the insurance carriers, not my clients. My goal is to help you find the lowest premiums and provide the best personal service possible, year after year. Unlike many agents, I won’t do a magic act and disappear after you sign up! 🙂

If you enjoyed this blog and found it helpful, please leave your comments, questions, or feedback below and feel free to share this article with your friends!

Thank you!

Ron Lewis
Ron@RonLewisInsurance.com
www.MedigapShopper.com
(760) 525-5769 – Cell
(866) 718-1600 – Toll-free

Switching from Medicare Advantage to Medigap in California: What You Need to Know

Each year, many people in California decide to leave their Medicare Advantage (Part C) plan and return to Original Medicare (Part A and Part B) with a Medicare Supplement (Medigap) plan. Often, this happens when premiums, copays, or out-of-pocket costs increase, or when clients find their favorite doctors or hospitals are no longer in their plan’s network.

If you’ve ever wondered how to switch from Medicare Advantage to Medigap, it’s important to understand how the process works, and the potential challenges if you have existing health conditions.

You Can Switch Back to Original Medicare — But You’re Not Automatically Guaranteed Medigap Approval

You can drop your Medicare Advantage plan and go back to Original Medicare during certain times of the year, such as the Annual Election Period (AEP), which goes from October 15th through December 7th every year or during the Medicare Advantage Open Enrollment Period, which goes from January 1st through March 31st.

However, many people are surprised to learn that once they return to Original Medicare, they must apply separately for a Medicare Supplement plan, and approval is not guaranteed. In most cases, insurance companies can review your health history, which is called “medical underwriting,” and deny coverage if you have serious or chronic health conditions. That’s why timing and knowing the rules can make all the difference.

Medicare Guaranteed Issue Rights: The Hidden Opportunities

Here’s the good news… even if you have health problems, there are special Guaranteed Issue (GI) rights or situations that often let you enroll in a Medigap plan without health questions or underwriting.

These rights apply in specific situations and many beneficiaries don’t realize they qualify. Some are tied to Medicare Advantage plan changes, others to state-specific protections. In California, there are several lesser-known GI opportunities that can help people switch to Medigap coverage, even when they’ve been told “no” before.

I work with clients every year who thought they couldn’t qualify due to health issues and I’ve helped them get accepted for Medicare Supplement coverage using legitimate Guaranteed Issue options that most agents aren’t aware of or don’t mention to their clients.

Why Work with a Specialist Who Knows the California Rules

The Medicare rules in California are unique. Between the California Birthday Rule and other state-specific guaranteed issue protections, there are several ways to save money and secure coverage without medical underwriting.

As an independent Medicare Supplement insurance specialist, I work with all the major insurance carriers throughout California, Nevada, and several other states. My goal is simple. I want to help you find the best Medicare Supplement plan with the lowest premium and the most reliable coverage, year after year.

Let’s See What You Qualify For

If you’re considering leaving your Medicare Advantage plan or want to see if you qualify for a Guaranteed Issue Medicare Supplement, don’t wait until it’s too late.

There is no cost for my help. I’m paid by the insurance carriers, not my clients. I can review your situation, identify any Guaranteed Issue opportunities, and help you apply for the coverage that fits your needs and budget.

Contact me today to learn your options and see how much you could save on your Medicare Supplement plan.

About the Author

As an independent Medicare Supplement insurance specialist, I work with all the major insurance carriers throughout California, Nevada, and several other states. I shop around for my clients every year during their annual open enrollment period under the California Birthday Rule to help them save money on their Medicare Supplement premiums. Many of my clients have saved hundreds, even thousands of dollars for the same exact plan and coverage! Please click here to read what my clients have to say about my services.

There is no charge for my services as I’m compensated by the insurance carriers, not my clients. My goal is to help you find the lowest premiums and provide the best personal service possible, year after year. Unlike many agents, I won’t disappear after you sign up!

If you enjoyed this blog and found it helpful, please leave your comments, questions, or feedback below and feel free to share this article with your friends!

Thank you!

Ron Lewis
Ron@RonLewisInsurance.com
www.MedigapShopper.com
(760) 525-5769 – Cell
(866) 718-1600 – Toll-free

Why You May Be Better Off Choosing Your Own Medicare Prescription Drug Plan (Part D)

If you’ve ever tried to compare Medicare Prescription Drug Plans (PDPs), also known as Medicare Part D, you know how confusing it can be. There are dozens of options, and each plan has its own list of covered drugs (called a formulary), preferred pharmacies, and cost structure. What looks like a small difference in co-pays or premiums can easily add up to hundreds of dollars over the course of a year.

Why Most Agents No Longer Sell Prescription Drug Plans

You might assume that a licensed insurance agent can help you find the best plan, and in the past, many could. However, today’s system makes that much more difficult. Because of how Medicare’s certification and contracting rules work, most independent agents are not certified with every drug plan available in your area. They can only recommend or enroll you in a limited number of specific plans they are contracted with and certified to sell.

If another company offers a plan with lower co-pays or better coverage for your medications, your agent may not even be allowed to discuss it with you. Why? Because they don’t get paid for selling plans they’re not certified or contracted to represent. Even if they know a different plan would save you money, compliance rules and commission structures prevent them from showing it to you.

The Hidden Time and Cost Burden on Agents

Before an agent can help anyone with a PDP or a Medicare Advantage (MA) plan, they must complete extensive training and certification every year. This starts with the AHIP certification exam, which takes many agents 10–20 hours of study time to complete. The AHIP exam covers topics such as Medicare compliance, plan rules, CMS marketing guidelines, etc.

But that’s only the beginning. Agents must also spend time studying and taking individual certification exams for EVERY insurance company whose plans they want to sell. Each carrier’s certification process is different. Some require several hours of training, testing, and annual renewal. Altogether, a well-rounded agent could easily spend 50+ hours each year just keeping up with certifications before they can even begin helping clients.

Then there are the CMS compliance rules, which now require all sales calls related to PDPs and MA plans to be recorded and stored securely for 10 years! The added administrative burden and potential liability make it even less practical for agents to offer these plans, especially since commissions for prescription plans are typically under $100 per year per client. Many agents have simply decided that it’s not worth the time and effort.

How You Can Shop and Enroll in a Drug Plan On Your Own

Fortunately, Medicare makes it easy for you to shop around on your own and sign up for a prescription drug plan at www.Medicare.gov by using the exact same tool that agents use.

This past year, I put together a short video that explains how to shop for and sign up for a Medicare prescription drug plan using the Medicare Plan Finder tool. It’s actually very easy, and there aren’t any significant changes since last year. Please click here to watch the video.

The Medicare Plan Finder is available 24/7 and it is updated every fall with the latest plan information. It allows you to make an informed decision without pressure or bias, and without worrying whether your agent is certified to sell a particular plan.

Review Your Coverage Each Fall

Even if you’re happy with your current PDP, it’s important to review your coverage each year during the Annual Election Period (AEP), which goes from October 15th through December 7th each year. PDPs are annual contracts, and drug prices, plan premiums, and pharmacy networks can change every year. What’s good this year may not be so good next year.

It only takes about 15 to 20 minutes to shop around and review your PDP options, and it could save you literally hundreds of dollars and ensure you have the right coverage for your specific prescriptions.

The Bottom Line

Most Medicare agents are honest, hardworking professionals who want to help their clients, but the system is stacked against them when it comes to prescription drug plans. Between certification costs, compliance rules, and low commissions, many agents have chosen to focus on Medicare Supplements, Medicare Advantage plans, or other types of insurance products instead.

By learning how to shop for your own prescription drug coverage at Medicare.gov, you can take control of your health care costs, stay informed, and make sure you’re always getting the best prescription drug plan every year.

About the Author

As an independent Medicare Supplement insurance specialist, I work with all the major carriers throughout California, Nevada, and several other states. I shop around for my clients every year during their 60-day annual open enrollment period under the California Birthday Rule to help them save money on their Medicare Supplement premiums. Many of my clients have saved hundreds, even thousands of dollars on the same exact plan and coverage! Please click here to see what my clients have to say about my services.

There is no charge for my services as I’m compensated by the insurance carriers, not my clients. My goal is to help you find the lowest premiums and provide the best personal service possible—year after year. Unlike many agents, I won’t disappear after you sign up!

If you enjoyed this blog and found it helpful, please leave your comments, questions, or feedback below and feel free to share this article with your friends!

Thank you!

Ron Lewis
Ron@RonLewisInsurance.com
www.MedigapShopper.com
(760) 525-5769 – Cell
(866) 718-1600 – Toll-free

Medicare Prescription Drug Plans

When Is the Best Time To Sign Up For a Medicare Prescription Drug Plan?

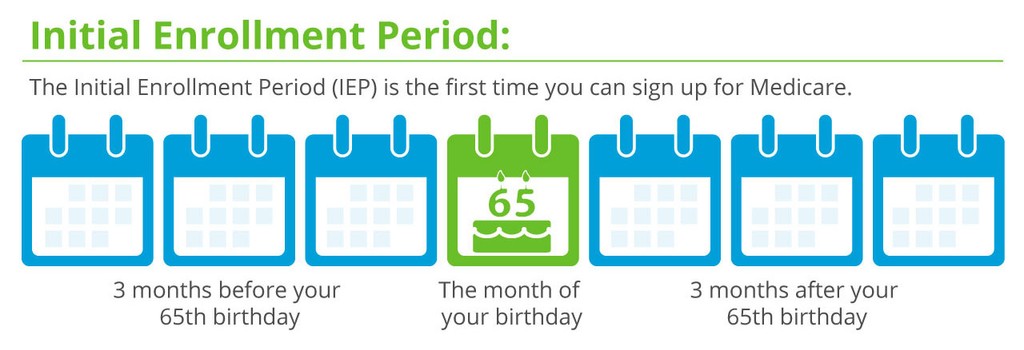
If you are eligible for Medicare, you can generally sign up for Medicare Part D, also known as a Medicare Prescription Drug Plan (PDP) during the Initial Enrollment Period (IEP), which is the 7-month period that starts 3 months before the month you turn 65, includes the month you turn 65, and ends 3 months after the month you turn 65.

In addition, you can also sign up for a Medicare PDP during the Annual Enrollment Period (AEP), which runs from October 15th through December 7th each year. During this period, you can join, switch, or drop your Medicare PDP.

NOTE: The AEP is the annual open enrollment period to change prescription drug plans and Medicare Advantage plans, not Medicare Supplement plans. If you have a Medicare Supplement, you can change it any time of the year. If you change your Medicare PDP or your Medicare Advantage plan during the AEP, the new coverage will begin on January 1st of the following year.

If you don’t enroll in a Medicare PDP during your IEP or when you first become eligible for Medicare, you may be subject to a late enrollment penalty if you later decide to enroll in a plan.

What Happens If I Don’t Sign Up For a Prescription Drug Plan During the Initial Enrollment Period?

If you miss your IEP to sign up for a Medicare PDP, you generally have to wait until the AEP to sign up for a plan unless you qualify for a Special Enrollment Period (SEP). A SEP is a time outside of the IEP or AEP when you can make changes to your Medicare coverage.

Here are some examples of events that may qualify as a SEP:

  • Moving to a new address: If an individual moves outside of their Medicare Advantage plan’s service area, they may be eligible for a SEP to enroll in a new plan.
  • Losing other health coverage: If an individual loses coverage from an employer, union, or other health plan, they may be eligible for a SEP to enroll in a Medicare Advantage plan or a Medicare Part D prescription drug plan.
  • Gaining new health coverage: If an individual gains coverage from an employer, union, or other health plan, they may be eligible for a SEP to disenroll from their Medicare Advantage plan or their Medicare Part D prescription drug plan.
  • Becoming eligible for Medicaid: If an individual becomes eligible for Medicaid, they may be eligible for a SEP to enroll in a Medicare Advantage plan or a Medicare Part D prescription drug plan.
  • Moving into or out of a nursing home or long-term care facility: If an individual moves into or out of a nursing home or long-term care facility, they may be eligible for a SEP to enroll in or change their Medicare coverage.

Not all events will qualify an individual for a Medicare SEP, and the rules and timelines for each SEP can vary. It’s always a good idea to check with Medicare or a licensed insurance agent to confirm eligibility and understand the options available. If you do qualify for a SEP, you have a limited time period to enroll in a Medicare PDP. The length of the SEP varies depending on the reason for the SEP. If you don’t qualify for a SEP, you will have to wait until the next AEP to sign up for a Medicare PDP.

When Do I Need to Sign Up For a Prescription Drug Plan When Coming Off An Employer Health Plan?

If you are coming off an employer health plan that included “creditable” prescription drug coverage and you enroll in a Medicare PDP within 63 days of losing your employer coverage, you generally will not be subject to a late enrollment penalty. Creditable coverage is prescription drug coverage that is expected to pay, on average, at least as much as Medicare’s standard prescription drug coverage. Your employer should notify you each year if your prescription drug coverage is creditable.

If you do not enroll in a Medicare PDP within 63 days of losing your employer coverage, you will be subject to a late enrollment penalty if you later decide to enroll in a plan. The penalty would be calculated based on the number of full months you were eligible for a Medicare PDP but did not have creditable prescription drug coverage.

Important: If you enroll in a Medicare Prescription Drug Plan after the 63-day period, you may also have a gap in coverage, which could result in higher out-of-pocket costs for your prescription medications.

What Is the Medicare Prescription Drug Plan Late Enrollment Penalty?

The Medicare PDP late enrollment penalty is a fee that may be imposed on individuals who enroll in a Medicare PDP after their IEP has ended, and who do not have creditable prescription drug coverage from another source (such as an employer).

The penalty is calculated based on the number of months that an individual went without creditable coverage, and is added to the monthly premium for the Medicare PDP. The penalty amount may increase each year, and the penalty is paid for as long as the individual is enrolled in a Medicare PDP. There are some exceptions to the penalty, such as if an individual had a valid reason for delaying enrollment, such as being covered under a spouse’s health insurance plan, etc.

How To Calculate the Medicare Prescription Drug Plan Late Enrollment Penalty

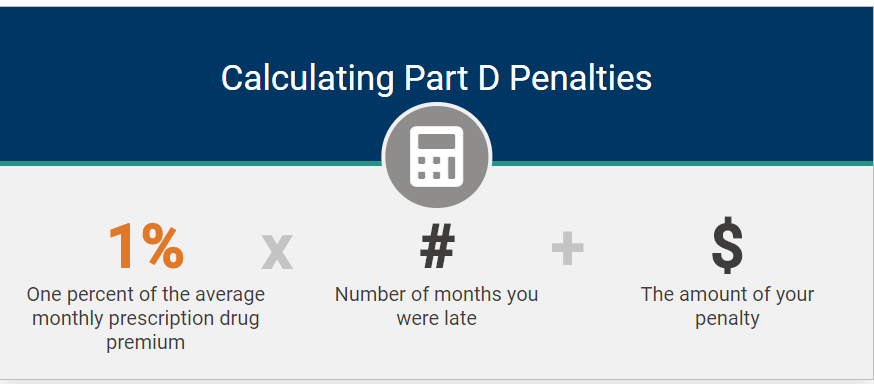
The Medicare PDP late enrollment penalty is calculated by multiplying 1% of the “national base beneficiary premium” ($32.74 in 2023) by the number of full, uncovered months that an individual did not have creditable prescription drug coverage.

The national base beneficiary premium is the average monthly premium for a Medicare prescription drug plan in the United States, as determined by the Centers for Medicare & Medicaid Services (CMS). The amount of the penalty may increase each year, as the national base beneficiary premium changes.

Here’s an example of how to calculate the penalty:

In 2023, the national base beneficiary premium is $32.74. If an individual goes without creditable prescription drug coverage for 12 months (a full year) after their IEP has ended, the penalty would be 1% of $32.74, or approximately $0.33 per month. Therefore, the penalty amount would be $3.96 ($0.33 x 12 months = $3.96), and this amount would be added to the individual’s monthly premium for their Medicare PDP.

If an individual goes without creditable prescription drug coverage for a shorter period of time, the penalty amount would be lower, based on the number of full, uncovered months, etc. The late enrollment penalty is added to your monthly premium for as long as you have Medicare PDP coverage.

NOTE: The penalty is permanent and may increase each year based on changes to the national base beneficiary premium.

To avoid the late enrollment penalty, it’s important to enroll in a Medicare PDP during your IEP, or when you first become eligible for Medicare, or within 63 days of coming off of an employer health plan, even if you don’t currently take any prescription medications. In California, you can get a Medicare PDP for as low as $4.50 per month!

How Do I Know If I Have to Pay a Penalty?

After you join a Medicare PDP, the plan will tell you if you have to pay a penalty and what your premium will be. In general, you’ll have to pay this penalty for as long as you have a Medicare drug plan.

What If I Don’t Agree With the Late Enrollment Penalty?

You may be able to ask for a “reconsideration.” Your drug plan will send information about how to request a reconsideration. Complete the form, and return it to the address or fax the number listed on the form. You must do this within 60 days from the date on the letter telling you that you have to pay a late enrollment penalty. Also send any proof that supports your case, like a copy of your notice of creditable prescription drug coverage from an employer or union plan.

Do I Have to Pay the Penalty Even If I Don’t Agree With It?

By law, the late enrollment penalty is part of the premium, so you must pay the penalty with the premium. You must also pay the penalty even if you’ve asked for a reconsideration. Medicare PDP’s can dis-enroll members who don’t pay their premiums, including the late enrollment penalty portion of the premium.

How Soon Will I Get a Reconsideration Decision?

In general, Medicare makes reconsideration decisions within 90 days. They will try to make a decision as quickly as possible. However, you may request an extension. Medicare may sometimes take an additional 14 days to resolve your case.

If Medicare decides that all or part of your late enrollment penalty is wrong, Medicare will send you and your drug plan a letter explaining its decision. Your Medicare PDP will remove or reduce your late enrollment penalty. The plan will send you a letter that shows the correct premium amount and explains whether you’ll get a refund. If Medicare decides that your late enrollment penalty is correct, Medicare will send you a letter explaining the decision, and you must pay the penalty.

To Make a Long Story Short…

To avoid the Medicare late enrollment penalty…

  • When you are turning 65, the best time to sign up for a Medicare PDP is during the 7-month IEP.
  • If you or your spouse is coming off of a creditable employer health plan, the best time to sign up for a Medicare PDP is during the 63 days after your employer coverage ends.

About Me

I hope that you have found this information to be interesting and informative. I’m an independent insurance agent with over 15 years of experience specializing in Medicare Supplement insurance, primarily in California. As an independent agent, I work with most of the major insurance carriers including Mutual of Omaha, Cigna, Blue Shield of CA, Anthem Blue Cross, Health Net, Aetna, etc. I have hundreds of clients, and I shop around for them every year around their birthday. Please click here to see some of my client testimonials.

If you have any questions, or if you know anyone that is turning 65 or starting Medicare, or if you would like for me to shop around for you, I’m happy to help, and there is no charge for my service!!! Please feel free to contact me! Also, please feel free to forward this blog on to anyone you know who may be interested.

Thank you!

Ron Lewis
CA agent #0B33674
NV agent #3822123

Ron@RonLewisInsurance.com
866.718.1600 (Toll-free)
760.525.5769 (Cell)
www.MedigapShopper.com